Ore Daily BriefChile's cut is twice the world surplus. Ero's mined gold barely pays.Cochilco's Chile downgrade outweighs the surplus it forecasts, Indonesia is already 7–12% over its nickel ore quota, and Xavantina's mined ounces clear $320 at spot. Midterms today; SSR reports after the close.
2.3xChile 2026 cut vs world surplus330 kt vs 144 kt, Cochilco
$320Xavantina mined margin/ozQ3 AISC $3,607 vs spot $3,927
7–12%Indonesia nickel ore over quota~290 Mt vs 260–270 Mt RKAB
Today
Today — US midterm elections. Traders price a 74% chance of a December Fed hike, and spot gold at $3,926.52 sits just 1.5% above Friday's $3,870.27 one-year low.
10:30 AM ET — Ero Copper Q3 call (details). Nine-month copper of 52,947 t means the 67,500 t low end needs only 14.6 kt in Q4, 21% below Q3's 18,345 t; the top end needs 24.6 kt, 34% above it.
After the close — SSR Mining Q3; call 5:00 PM ET. H1 output of 211,873 oz gold equivalent leaves 119–162 koz a quarter for H2 under the 450–535 koz guide, 17% to 58% above Q2's 101,959 oz. Q2 AISC of $2,622 leaves $1,305/oz at today's spot.
Copper
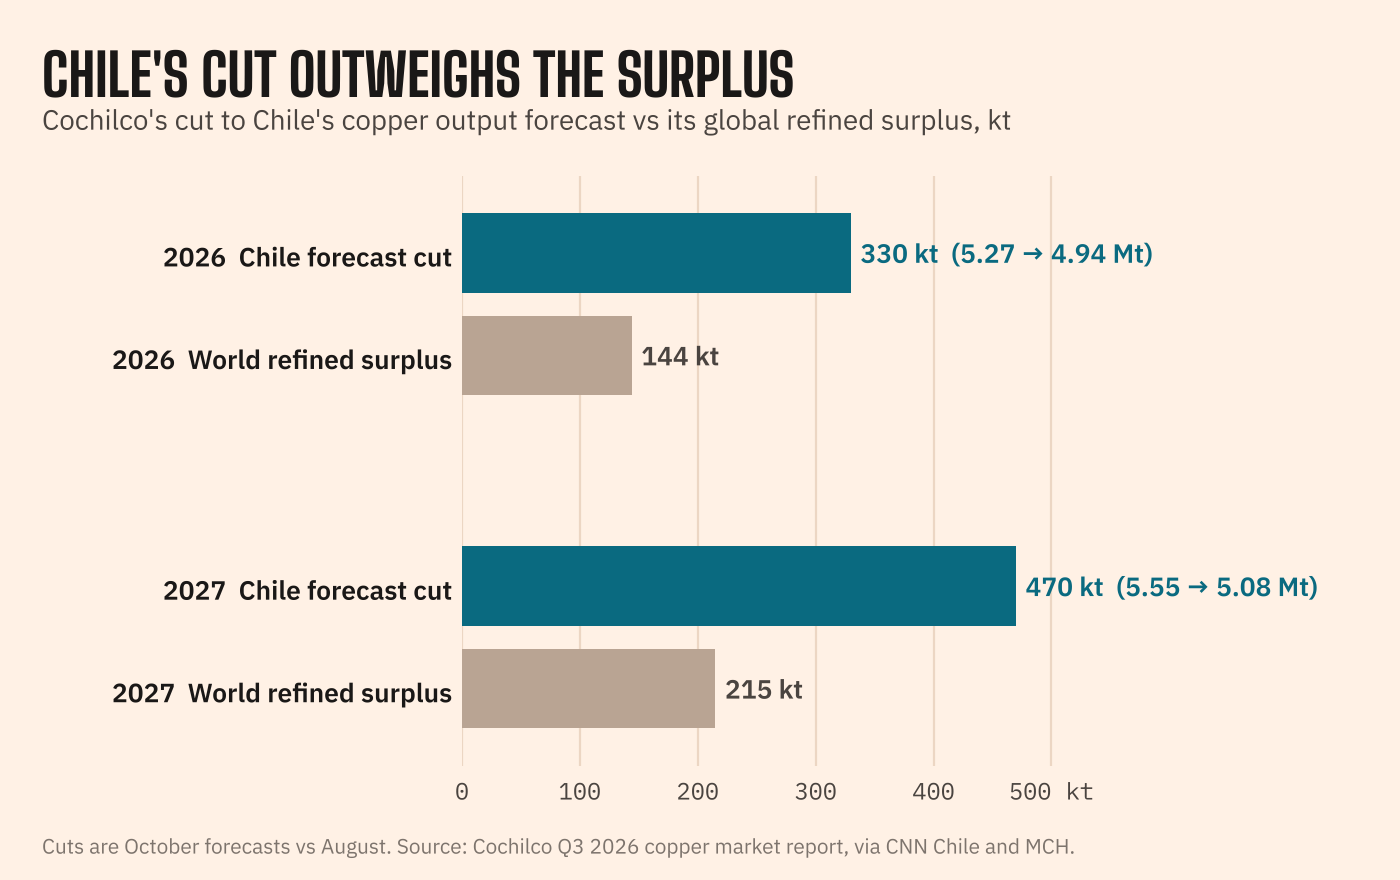
Chile's cut is bigger than the world surplus. Cochilco took 330 kt off Chile's 2026 forecast (5.27 Mt to 4.94 Mt), 2.3 times its own 144 kt global refined surplus. The 2027 cut, 470 kt (5.55 to 5.08 Mt), is 2.2 times the 215 kt surplus it sees then.
Less Chilean copper, lower prices anyway. Cochilco's 2027 average of $5.95/lb is 9.8% below the $6.60 last quote in its report, and its 2026 call of $6.18 is barely above the $6.14 year-to-date average.
Precious
Ero's mined gold barely pays. Xavantina's Q3 mined AISC of $3,607/oz leaves about $320 at spot of $3,926.52; the new $3,300–3,600 guide leaves $327–627. Historic concentrate, at $710 AISC, made 69% of Q3 gold.
Fenn-Gib's capex per ounce.C$450M for about 71,300 oz a year in the first six years is about C$6,300 per annual ounce, or roughly US$4,400 at the study's exchange rate.
Hike odds eased, the price didn't. FedWatch December hike odds slipped to 76.6% from 80% a week earlier, yet spot gold is still 30% below January's $5,608.35 record.
Critical minerals
Indonesia is already over its own quota. The ministry expects about 290 Mt of nickel ore this year against a 260–270 Mt RKAB, 7–12% over. At the same grade, trimming to quota removes roughly 180–270 kt of nickel from 2025's 2.6 Mt, 5–7% of world supply (USGS).
Next
Wed Nov 4, after the close — Fortuna and OceanaGold Q3. Calls Thu at 12:00 PM ET and 10:00 AM ET; more gold costs to set against spot under $4,000.
Fri Nov 6, 8:30 AM ET — US October payrolls (BLS schedule). The next test of the 74–77% December hike pricing.
Tue Nov 10, 8:30 AM ET — US October CPI (BLS schedule). The last big print before markets settle December hike odds.
Ore Daily analysis of public data. Figures are as reported by the sources.
Top 5
1
Indonesia tells nickel miners to rein in output and floats a smelter moratorium
At the Minerba Convex in Jakarta on Nov 2, ESDM Minister Bahlil Lahadalia blamed Indonesian overproduction for nickel at about US$15,000/t (below US$16,000), citing a global oversupply of about 800,000t.He told the minerals and coal DG Tri Winarno to control output tightly through RKAB approvals. He also asked for a study of a moratorium on new smelters that make only semi-finished products, which he put at 50–60% of domestic processing output. This is the first time the government has framed RKAB explicitly as a supply-management tool, and a moratorium would hit NPI/matte/MHP expansion plans. No volumes given. Indonesia, nickel.
Indonesia is already over its own quota. The ministry expects about 290 Mt of nickel ore this year against a 260–270 Mt RKAB, 7–12% over. At the same grade, trimming to quota removes roughly 180–270 kt of nickel from 2025's 2.6 Mt, 5–7% of world supply (USGS). Smelters under construction add about 320 Mt a year of ore capacity, more than this year's whole output; existing plants could take 415 Mt at full rates. The $15,510 Oct 2 low was 10% under the 2026 average (nickel data).
2
Cochilco cuts Chile's copper output forecasts sharply and raises its price calls
The world's top producer is on course for its weakest year in more than two decades, and the 2027 recovery has been pushed back too.The forecast was released Oct 30–Nov 1 and was not in previous digests. Chile, copper.
Output: 2026 now 4.94Mt, down 8.4% (August: 5.27Mt, -2.6%). 2027 is 5.08Mt (was 5.55Mt).
Prices: 2026 average lifted to US$6.18/lb (from 5.95), 2027 to US$5.95/lb (from 5.10).
Jan–Sep output was 3.63Mt (-8.5%). Escondida, Spence and Codelco account for 77% of the drop.
Global refined surplus is only 144kt in 2026 and 215kt in 2027.
Chile's cut is bigger than the world surplus. Cochilco took 330 kt off Chile's 2026 forecast (5.27 Mt to 4.94 Mt), 2.3 times its own 144 kt global refined surplus. The 2027 cut, 470 kt (5.55 to 5.08 Mt), is 2.2 times the 215 kt surplus it sees then. The 2026 surplus is just 0.5% of 27.50 Mt of refined demand, and Cochilco says demand 1% above forecast would turn it into a deficit near 65 kt. Even cut, Chile is 21% of the 23.30 Mt world mine output it forecasts.
3
Gold rebounds from its one-year low, then slips again ahead of the US midterms
Rate-hike pricing and deleveraging keep a lid on any recovery.Gold/silver.
Monday: spot rose 1.84% to $3,945.80 at 5:02 PM ET as oil fell more than 7% on US-Iran talk hopes.
Tuesday: it was back to $3,926.52 (-0.5%) by 0353 GMT. Silver was $49.71.
CME FedWatch puts the odds of a December rate hike at 74%.
Hike odds eased, the price didn't. FedWatch December hike odds slipped to 76.6% from 80% a week earlier, yet spot gold is still 30% below January's $5,608.35 record. Silver at $49.71 puts the gold/silver ratio at 79, up from about 78 in the Nov 2 Brief and 74 on Oct 26.
4
The biggest miners lost $226bn in value in October
MINING.COM's Top 50 fell 10% in October and is down $712bn (-26%) since its February peak, when the Iran war began.Losses included Kinross -17.3%, Antofagasta -16.1%, AngloGold -15.8%, Vale -15.4%, Rio -12.6% and Southern Copper -12.4%. Northern Star (+3.3%) was the only gainer in local currency. This is the scale of the de-rating behind last week's gold rout. Global.
Copper bounces on Monday, then falls on Tuesday with an AI-stocks selloff
Physical tightness in China is running against macro de-risking.Copper.
Monday: LME copper closed up 1.38% at $14,325.5/t. SMM put the 10,042-lot drop in open interest down to bears cutting positions.
Physical market: SMM's China social stocks were 66,900t, about 130kt below a year earlier.
Tuesday: Bloomberg reported copper and tin falling across base metals on a renewed AI-stocks selloff. Trading Economics showed COMEX down about 3% (untimed).
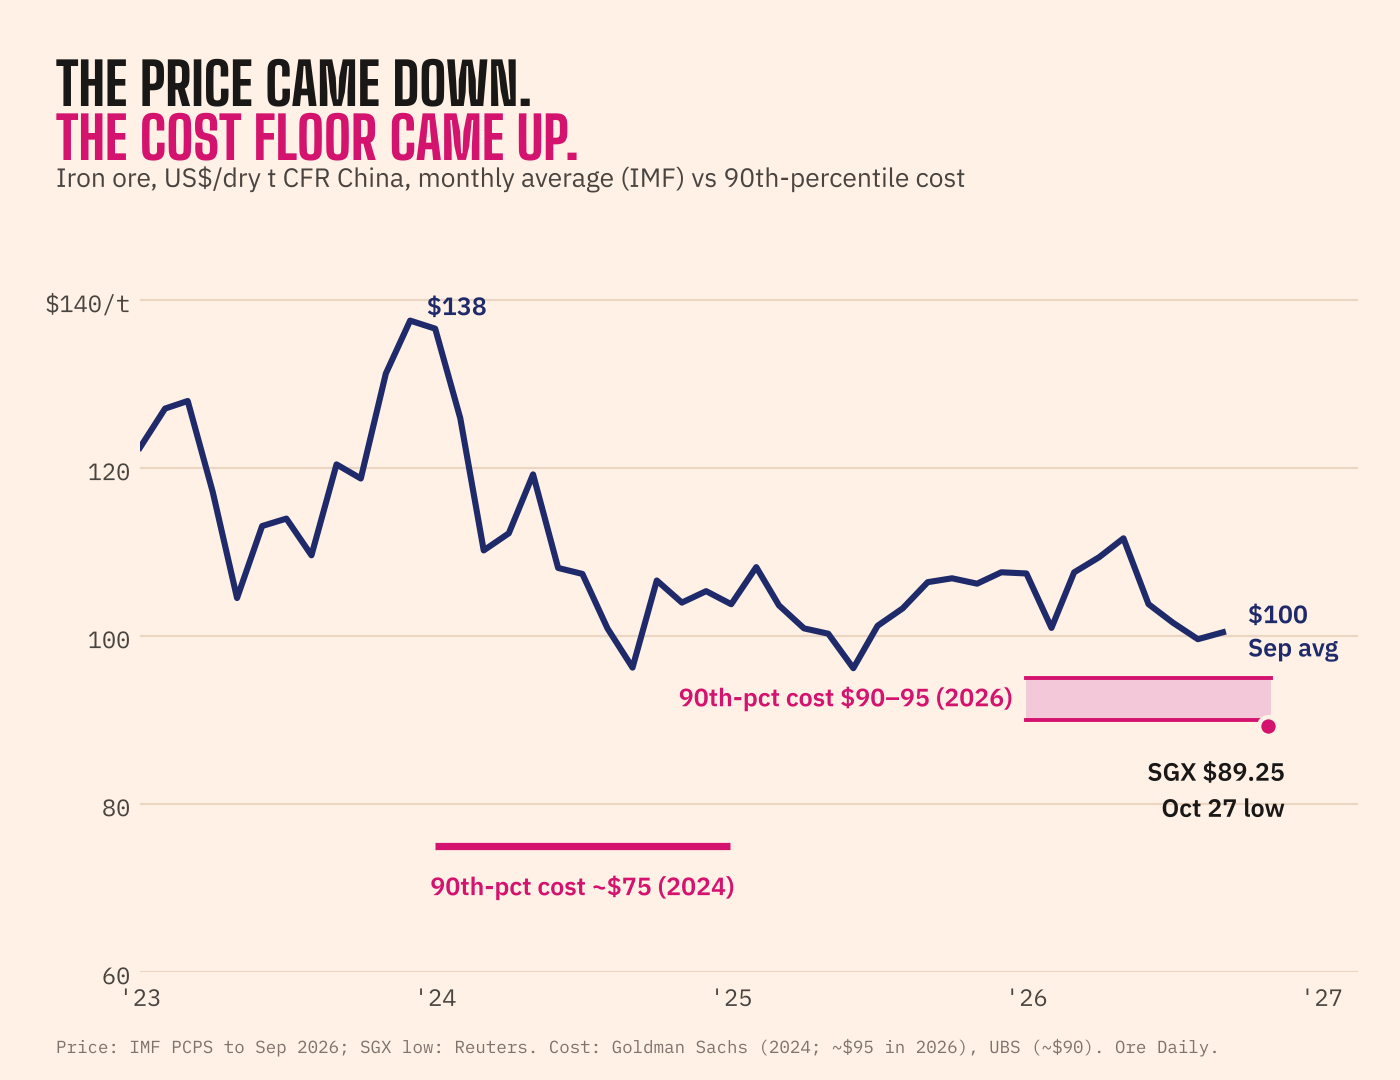
UBS puts 150–170Mt of supply under water below US$90. Cuts so far cover 15–20Mt. China's own mines are doing most of the retreating, and Simandou is still ramping up.
Bahlil said mining products and LNG must ship directly to the destination market, not through third countries.He also announced a 31 MMSCFD cut in pipeline gas to Singapore. No implementing regulation was cited. This hits trading hubs that re-route Indonesian ore, concentrate and NPI cargoes. Indonesia, minerals/LNG.
Indonesia's economic council backs RKAB nickel cuts
Septian Hario Seto of the National Economic Council (DEN) backed the ministry's plan to cut nickel output through RKAB.He said prices rose nearly 20% after the cut was flagged, without giving a period. Bahlil put demand at 3.5Mt/yr. Mining non-tax revenue was Rp141 trillion as of Oct 1, against a target of Rp160–165 trillion. Indonesia, nickel.
Indonesia plans to revise mining rules to favour the regions
Bahlil wants regions outside Jakarta, cooperatives, region-owned firms and small businesses to get more room under the permit rules.No details were given. Indonesia.
It is the fourth project in the "One Project, One Process" program, after PAK, Crawford and Great Bear.The Ministry of Energy and Mines leads the review. Construction is targeted for 2028 and first gold for 2030, at an initial capex of about C$450M. Ontario, gold.
Fenn-Gib's capex per ounce.C$450M for about 71,300 oz a year in the first six years is about C$6,300 per annual ounce, or roughly US$4,400 at the study's exchange rate. The study's base case uses US$3,100 gold; spot at $3,926.52 is 27% higher. Over the 14.3-year life, output averages 64,100 oz, so capex is C$7,000 per life-of-mine annual ounce.
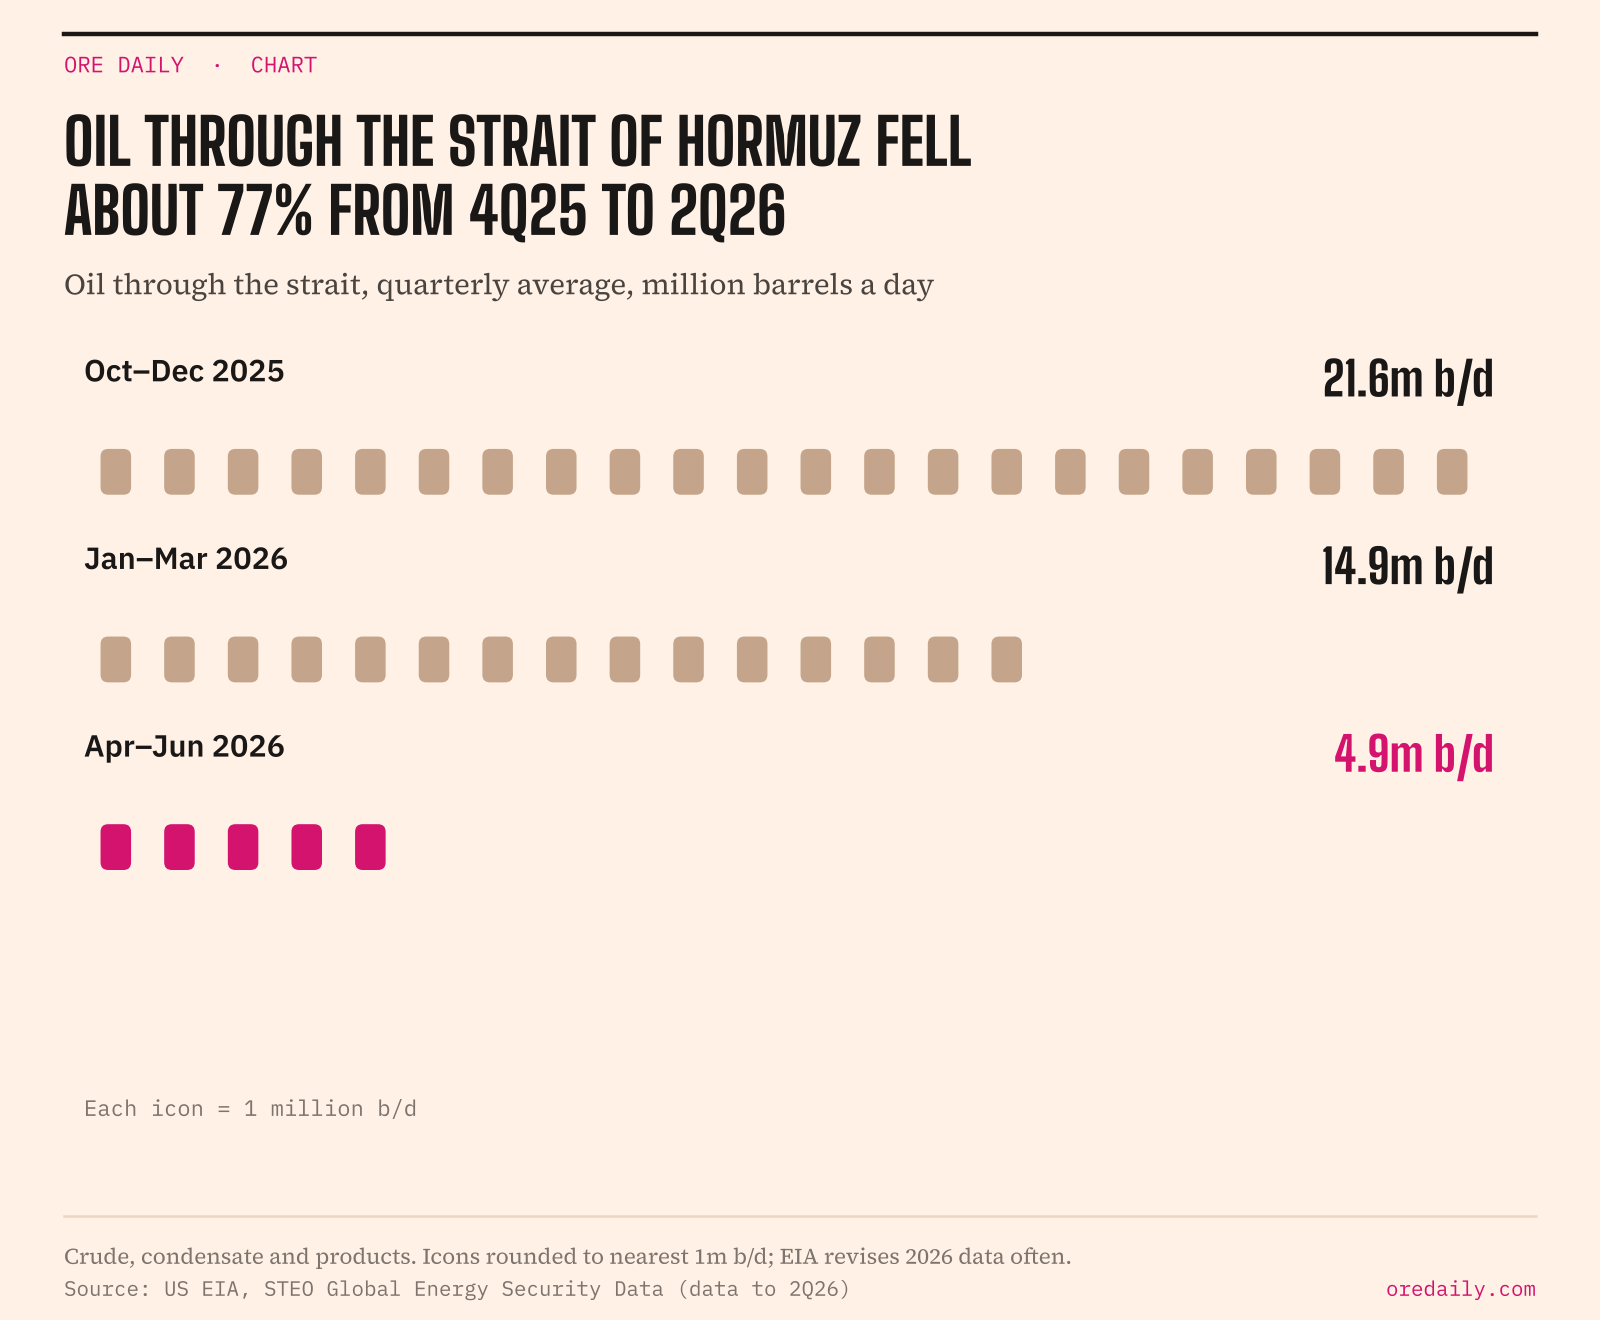
Chart of the dayOil through the Strait of Hormuz fell about 77% from 4Q25 to 2Q26
EIA estimates oil flows through the Strait of Hormuz averaged 21.6 million b/d in 4Q25, then 14.9 million b/d in 1Q26 and 4.9 million b/d in 2Q26; LNG flows fell from 10.5 Bcf/d to 0.8 Bcf/d over the same period.EIA
Production & trade data3
Chile's September Imacec: mining -12.1% y/y
Overall activity rose 0.2% y/y (+1.9% m/m seasonally adjusted).Finance Minister Jorge Quiroz blamed years of uncertainty and low investment for the mining slump and promised better numbers next year. This follows INE's September copper print reported yesterday. Chile, copper.
Ero's mined gold barely pays. Xavantina's Q3 mined AISC of $3,607/oz leaves about $320 at spot of $3,926.52; the new $3,300–3,600 guide leaves $327–627. Historic concentrate, at $710 AISC, made 69% of Q3 gold. Total 2026 gold guidance actually rises to 75,000–80,000 oz, but about 45,000 oz comes from stockpiled concentrate. Mined AISC guidance was $2,200–2,700 before this release.
Nornickel in data-centre talks
Vedomosti reports Rostelecom is talking to Nornickel about building an underground data centre.No figures given. Russia.
I ask our colleagues in the (nickel) mining and industrial sector to exercise some restraint.
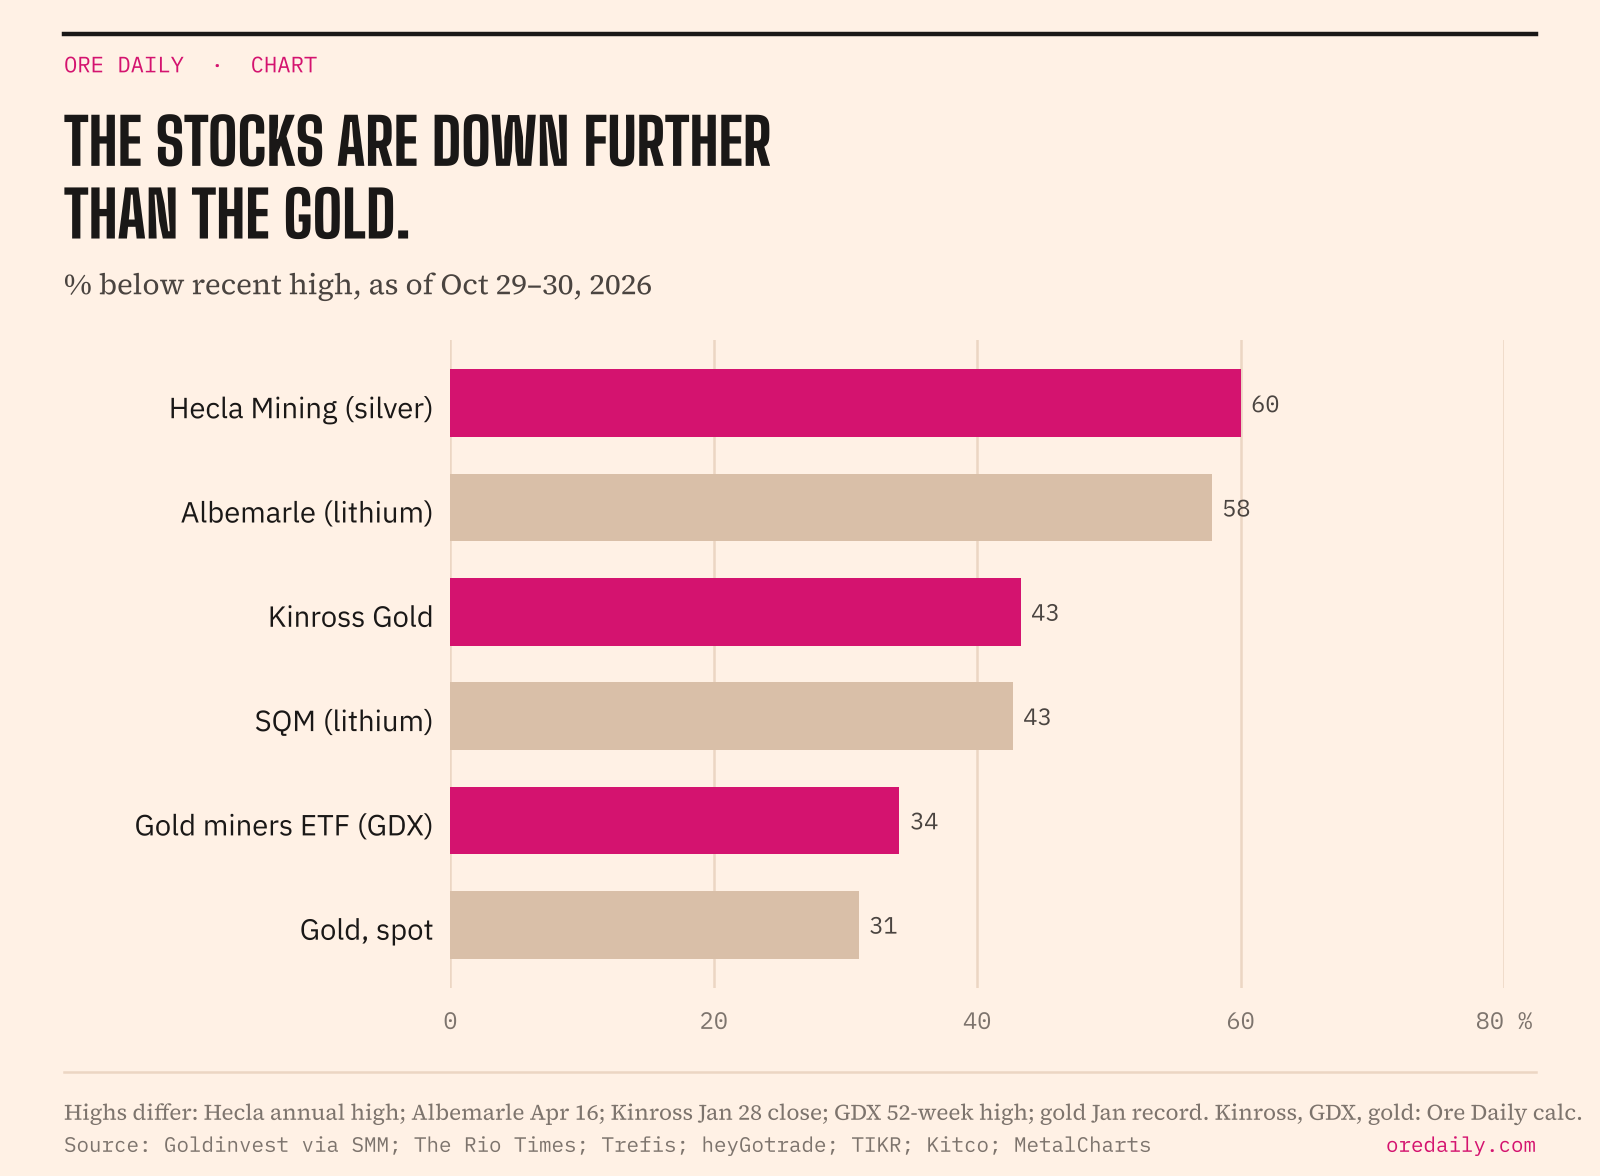
— Bahlil Lahadalia, Energy and Mineral Resources Minister, Indonesia, on nickel oversupply · ANTARA, Nov 2Ore Daily Perspective · Mining stocksMining stocks are falling harder than the metals they digTwo months of selling have taken a third off the gold miners' ETF and more than half off the worst-hit names. Copper, silver and lithium stocks are down too. Analysts are split on whether it is a reset or a bargain.
~34%Gold miners' ETF (GDX) below its 52-week highGold itself is ~31% off its record · Ore Daily calc.
4xSouthern Copper's Oct 30 drop vs the copper fund−7.4% vs −1.9% (CPER) · Ore Daily calc.
23%Senior gold producers' discount to 5-year cash-flow multiple6.8x vs 8.8x, Haywood
Copper:Southern Copper fell 7.4% and Freeport 5.6% on Oct 30, both to three-month lows, while the CPER copper fund lost 1.9%. The turn came on Sept 10, when copper broke from a record and Freeport, Teck, Anglo American, First Quantum and BHP each lost 6–7% in a day.
Kinross Gold: down 17% in October and closed at $21.60 on Oct 29, its lowest in a year, about 43% below its January high by Ore Daily's calculation. A September guidance cut and a Q3 revenue miss added to the gold slide.
Aura Minerals:down 15% on Oct 30 with no company news, about four times gold's 3.5% fall.
Forced selling: the tech and AI rout (Nasdaq −2.9% on Oct 30) brought margin calls, and investors sold what was liquid. "Clearly this has to do with a short-term liquidity problem," Peter Schiff wrote on X after gold's Oct 30 drop.
Cheap, by one measure: senior gold producers trade at 6.8x forward cash flow against an 8.8x five-year average, Haywood Securities said. "We view the recent selloff as a period of consolidation within an ongoing bull market in precious metals," its mining team wrote.
Not cheap everywhere: Newmont, Freeport, Kinross and Pan American Silver all show oversold readings, but Freeport and Southern Copper still trade at 21–24x forward earnings, Investing.com data show.
The caution: Commerzbank calls the panic selling overdone, but Saxo Bank's Ole Hansen sees silver at risk of a drop to the mid-$40s if trend-following funds keep selling.
Next: US midterms today, Albemarle's Q3 results Wednesday after the close, US jobs report Friday.
LME closed Monday at $14,325.5 (+1.38%); SHFE 2612 at 108,370 yuan (+0.73%).Yangshan EQ CIF was $94/t (+$4); the Shanghai cathode premium was 1,265 yuan.
Brent settled at $104.77 (-7.6%) on Monday on US-Iran talk hopes, and the US 10-year yield is near 4.9%.Trading Economics reports oil rebounding on Tuesday after reports of a US strike on Iran's Qeshm Island (single source). The US midterms are today.
"We expect gold to regain some ground"Ewa Manthey and Warren Patterson, ING
Gold settled 1.85% higher on Monday.ING expects some recovery after the correction, but says higher expected rates and a stronger dollar cap any lasting rebound.
Makoko District copper resources up 30% to ~12MtIvanhoe Mines (X, Oct 30)
The company post on its Western Forelands exploration project, next to Kamoa-Kakula in the DRC.The figure is from the company's post only; this run did not check it against a primary release.
64.9m @ 2.53% Cu, 0.873 g/t Au, 11.59 g/t Ag C3 Metals (TSXV: CCCM), Khaleesi, Cusco, Peru
Highest-grade hole yet at an emerging skarn discovery with limited previous drilling (drill).Hole KHZ5790-005 from 337.6m, including 23.3m @ 4.75% Cu, 1.837 g/t Au from 352.1m. True thickness is not determined, there is no resource yet, and holes -006 and -007 are pending. Copper-gold
91.44m @ 2.86 g/t Au Tectonic Metals (TSXV: TECT), Flat project, Black Creek target, Alaska
A ~100m step-out south of the 2025 Black Creek discovery hole (RC drill), which the company calls a second gold system at Flat.Hole CMR26-159 from 22.86m, including 41.15m @ 5.61 g/t and 13.72m @ 12.94 g/t. The hole ended in mineralization; true widths are unknown. Gold
First drill results at the prospect (RC drill).Hole FBRC0008 from 19m; 64m is the estimated true width. Released 5:00 AM ET Nov 2, just before the window, and not previously reported. Gold
First assays from maiden diamond drilling on the outcropping CaG vein (drill).Hole GLDD26_004 from 86.0m, including 2.9m @ 9.60 g/t Au. The other three holes returned 0.2–1.31 g/t, and the release is inconsistent on true width. Gold
10.60m @ 8.25 g/t Au Wesdome (TSX: WDO), Eagle River, Ontario
Western/down-dip extension of the 800 Zone (drill).Hole 26-925-10 from 298.8m (5.85 g/t capped), including 0.5m @ 143.0 g/t. A separate new east-west vein near the 805 ramp returned 2.00m @ 30.25 g/t from 4.0m. This is near-mine growth drilling and true widths are not stated. Gold
No new developments in the window on Teck's HVC strike, the Oyu Tolgoi restart, the Section 232 copper decision, Copper TC/RC 2027 or Russia's windfall tax.Smart-Lab expects second-reading amendments to the windfall tax around mid-to-late November; that is its estimate.
Coming up, next 7 days6
Tue Nov 3
US midterm elections; Ero Copper Q3 call at 10:30 AM ET; SSR Mining Q3.
Wed Nov 4
Lundin Mining Q3 after the close (call Thu Nov 5, 9:00 AM ET).
Thu Nov 5
Codelco EGM; IAMGOLD Q3; Critical Metals/European Lithium implementation; Fireweed Metals starts trading on the TSX (FWZ).
Fri Nov 6
Critical Metals moves to Nasdaq.
Mon Nov 9
Barrick Q3 (call 11:00 AM ET); ex-Ilva binding bids; Cornish Metals GM (about this date).
Tue Nov 10
China's pause on its October 2025 rare earth export controls reportedly ends (per secondary reports; no new MOFCOM notice found).
Disclaimer: This content uses AI to aggregate news from public sources. Summaries may contain errors and figures are as reported by the original source. Check the linked source before relying on any item. Not investment advice.