Metals & mining headlines

Ore PleaseDaily drill hits ›
Ore Daily BriefFirst Quantum has room to slow. Agnico's Barnat cut is worth about $390M a year.Q4 math on Wednesday's reports: First Quantum, Agnico and Kinross can hit their low ends on 9% less to 1% more than Q3. Today: GDP and PCE at 8:30 AM ET, Teck and Agnico calls at 11:00, Vale after the close.
$392MAgnico margin per year lost to the Barnat cut150 koz × Q3's $2,616/oz margin
−9%First Quantum Q4 vs Q3 at its low endNeeds 99 kt; Q3 was 109 kt
+67%First Quantum Q3 copper margin, y/y$2.06/lb; AISC up 40%

Today

  • 8:30 AM ET — US Q3 GDP (advance) and September PCE. The calendar forecast is +3.0% annualised, double Q2's 1.5%; PCE inflation lands at the same time, the day after the Fed's hawkish hold.
  • 9:15 AM ET — ECB decision. The deposit rate is 2.50% after a September hike; futures priced about 60% odds of a move to 2.75% as of Sept 24.
  • 11:00 AM ET — Teck Q3 call (webcast). Q3 copper of 115.7 kt was 15% below Q2's 135.9 kt; Quebrada Blanca, at 47.2 kt vs 55.8 kt, is 8.6 kt of the 20.2 kt drop. Teck still cut its net cash cost guide to US$1.80–2.00/lb from US$1.85–2.20.
  • 11:00 AM ET — Agnico Eagle Q3 call. Q3 AISC of $1,648/oz ran 6% above the top of the $1,400–1,550 full-year range it now expects to land near.
  • After the close — Vale 3Q26 results; call Fri 10:00 AM ET. The 335–345 Mt iron ore guide averages 84–86 Mt a quarter against Q2's 84.3 Mt, and equals about 13% of world mine supply (USGS).

Q4 math

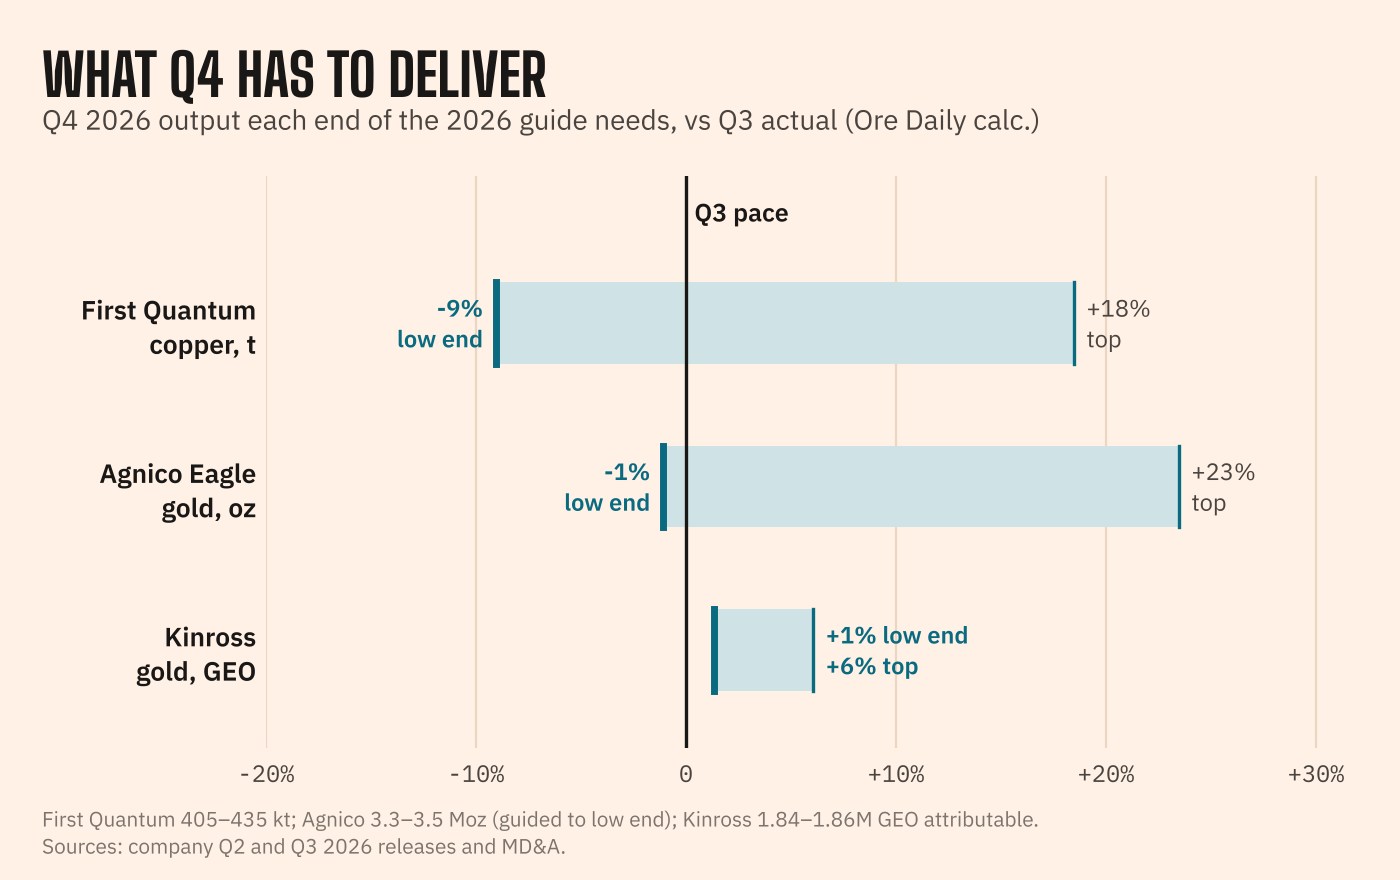
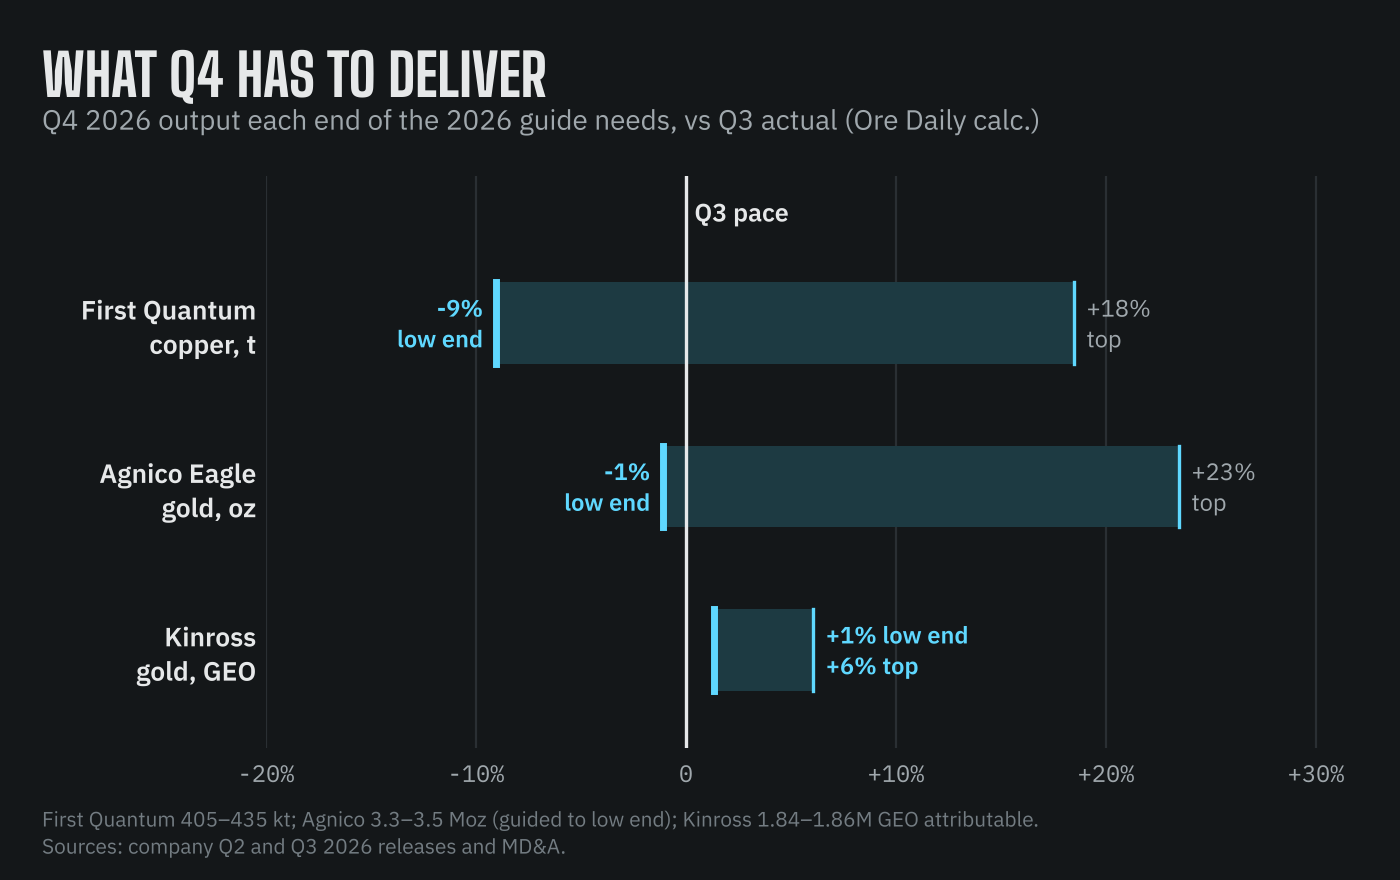
  • First Quantum can slow and still make its guide. Nine-month copper is 305.9 kt (96.5 kt and 100.5 kt in Q1 and Q2, 109.0 kt in Q3). The new 405–435 kt range needs 99–129 kt in Q4: the low end is 9% below Q3, the midpoint 5% above.
  • Agnico's low end needs no catch-up. Nine-month payable gold is 2.49 Moz (1,680,925 oz in H1 plus 814,012 oz in Q3). The 3.3 Moz low end needs 805 koz in Q4, 1% under Q3.
  • Kinross has to speed up, a little. 1,409,582 attributable GEO in nine months leaves 430–450 koz for Q4 under the 1.84–1.86M guide, 1–6% above Q3's 424,693. Nine-month AISC of $1,827 sits under the $1,850–1,900 range, so landing in it implies a costlier Q4.
Q4 2026 output needed to hit each end of 2026 guidance, compared with Q3 2026 output (Ore Daily calculation). First Quantum copper (405–435 kt): low end 9% below Q3, top 18% above. Agnico Eagle gold (3.3–3.5 Moz, guided to the low end): low end 1% below Q3, top 23% above. Kinross gold (1.84–1.86M attributable GEO): low end 1% above Q3, top 6% above.Q4 2026 output needed to hit each end of 2026 guidance, compared with Q3 2026 output (Ore Daily calculation). First Quantum copper (405–435 kt): low end 9% below Q3, top 18% above. Agnico Eagle gold (3.3–3.5 Moz, guided to the low end): low end 1% below Q3, top 23% above. Kinross gold (1.84–1.86M attributable GEO): low end 1% above Q3, top 6% above.

Copper

  • First Quantum's margin outran its costs. Q3 AISC of $4.30/lb was 40% above a year earlier ($3.07), but the net realised price of $6.36 rose 48%, so the margin rose 67% to $2.06/lb. The new $4.10–4.25 AISC guide leaves $2.35–2.50/lb at copper's $6.60 today.

Precious

  • Q4 starts $220–240/oz behind. Spot at $4,028 is $236 under Agnico's Q3 realised $4,264 and $221 under Kinross' $4,249. At Q3 AISC, that trims Agnico's margin 9% and Kinross' 10%.

Next

  • Fri Oct 30, 10:00 AM ET — Vale 3Q26 call (6-K). First look at iron ore realisations after fines averaged $95/t in Q2.
  • Fri Oct 30 — Cameco Q3 (Q2 release). H1 output of 10.1 Mlb leaves 9.4–11.4 Mlb for H2 under the 19.5–21.5 Mlb guide.
  • Mon Nov 9, 6:00 AM ET — Barrick Q3; webcast 11:00 AM ET. Gold's last major Q3 report, after Agnico and Kinross.

Sources: Ore Daily digest, Oct 29 · USGS MCS 2026 via Ore Daily data pages

Ore Daily analysis of public data. Figures are as reported by the sources.

Top 5

1
Glencore keeps its 2026 copper guidance but now expects the lower end of 810–870kt; cobalt output is down 52% this yearPerspective
Copper was 598.6kt in 9M (+3%; +12% after adjusting for the Mount Isa copper and Kidd exits), and Q3 was 201.6kt (+2% q/q). Cobalt was 13.7kt YTD versus 28.5kt. Glencore blames the DRC export quota regime and says cobalt is "increasingly being retained in solution" rather than made into hydroxide. Zinc 547.2kt (-23%) is now seen at the upper end of 700–740kt; nickel 54.6kt is mid-range. Ferrochrome rose 29% q/q as Boshoek and Wonderkop restarted. Marketing adj. EBIT is expected above $5bn. Antamina's higher copper grades added 32.3kt YTD, which puts more weight on the restart there. Global / copper, cobalt, zinc
Ore Daily PerspectiveGlencore now reports less cobalt than Congo lets it export

Glencore's reported cobalt fell to 3.5 kt in the third quarter. That pace is below its 2026 and 2027 export allocations. Glencore says its stockpiles in Congo cover its quotas in the near term.

3.5 ktGlencore cobalt output, Q3 2026vs 9.6 kt in Q3 2025, by Ore Daily's calculation
22.8 ktGlencore's 2026 DRC export allocationIncl. 2025 carryover; 18.8 kt in 2027
42%Congo's 2026 quota vs its 2025 mine output96.6 kt of ~230 kt (USGS)

The numbers

Glencore produced 13.7 kt of own-sourced cobalt in the first nine months, down 52% from 28.5 kt a year earlier. The third quarter gave 3.5 kt, down 20% from the second. That is down about 64% from 9.6 kt in the third quarter of 2025, by Ore Daily's calculation.

At the nine-month pace, Glencore would report about 18.3 kt this year. At the third-quarter pace, it is about 14 kt a year. Both sit below its 2026 export allocation of 22.8 kt, which includes 2025 carryover, and below the 18.8 kt allocated for 2027, by Ore Daily's calculation. In 2023 it produced 41.3 kt.
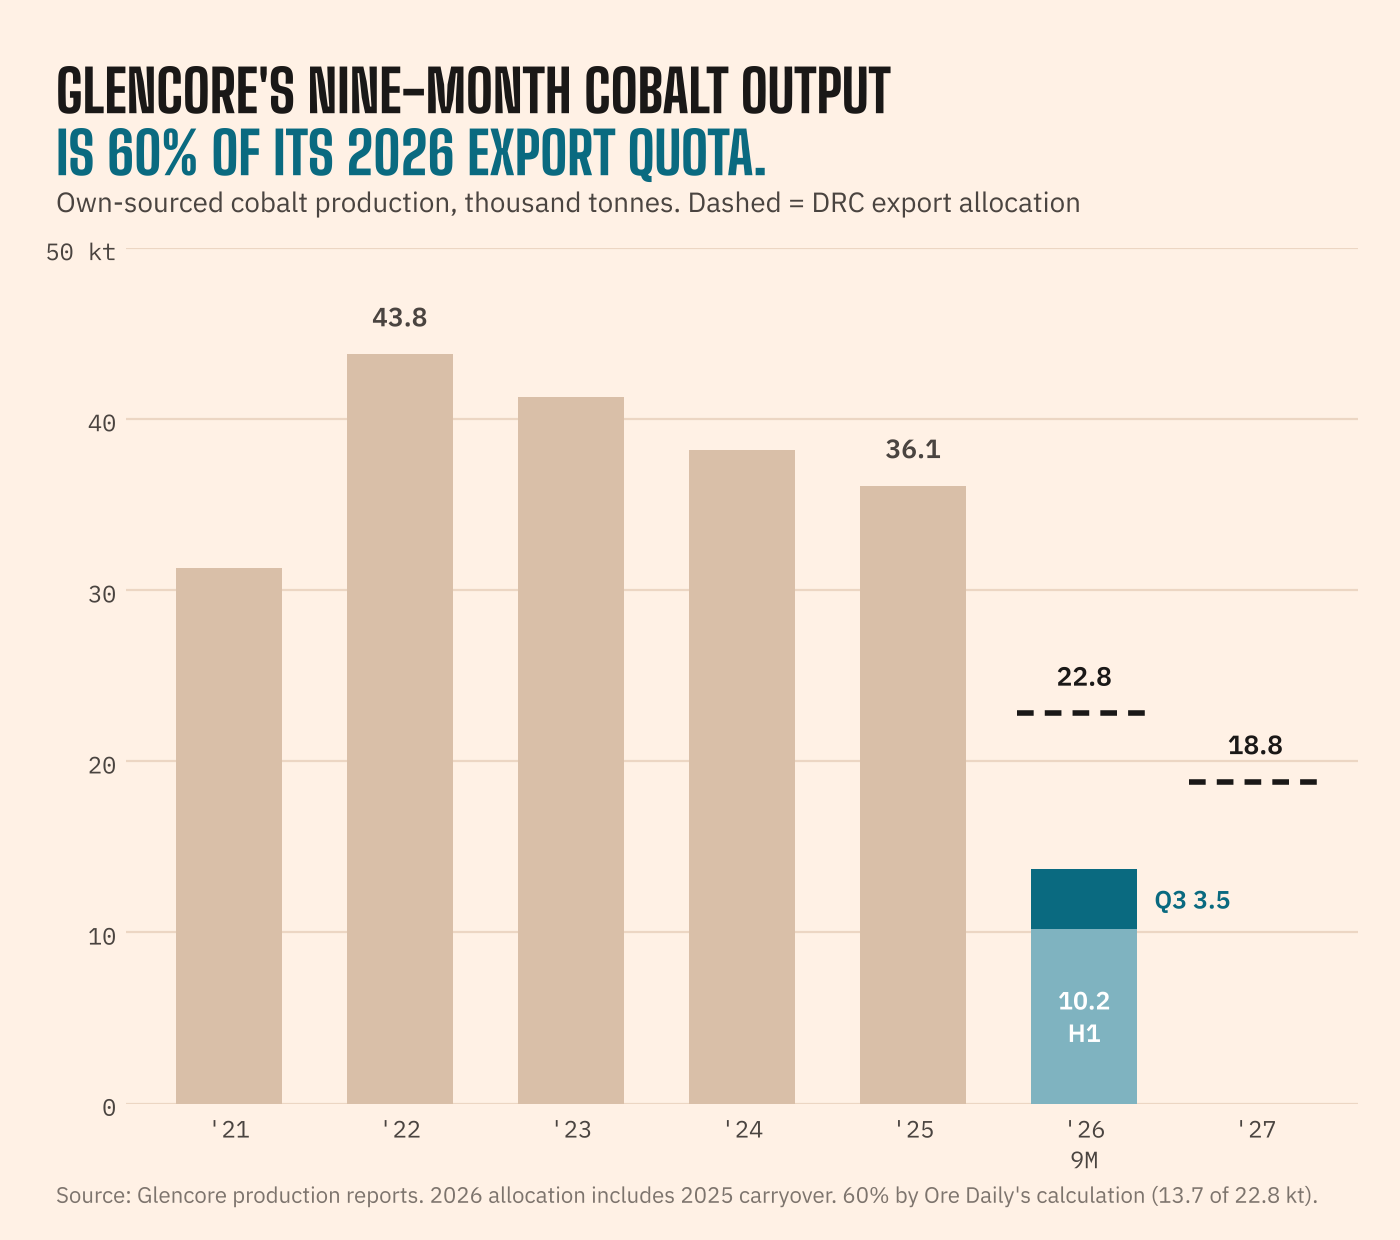
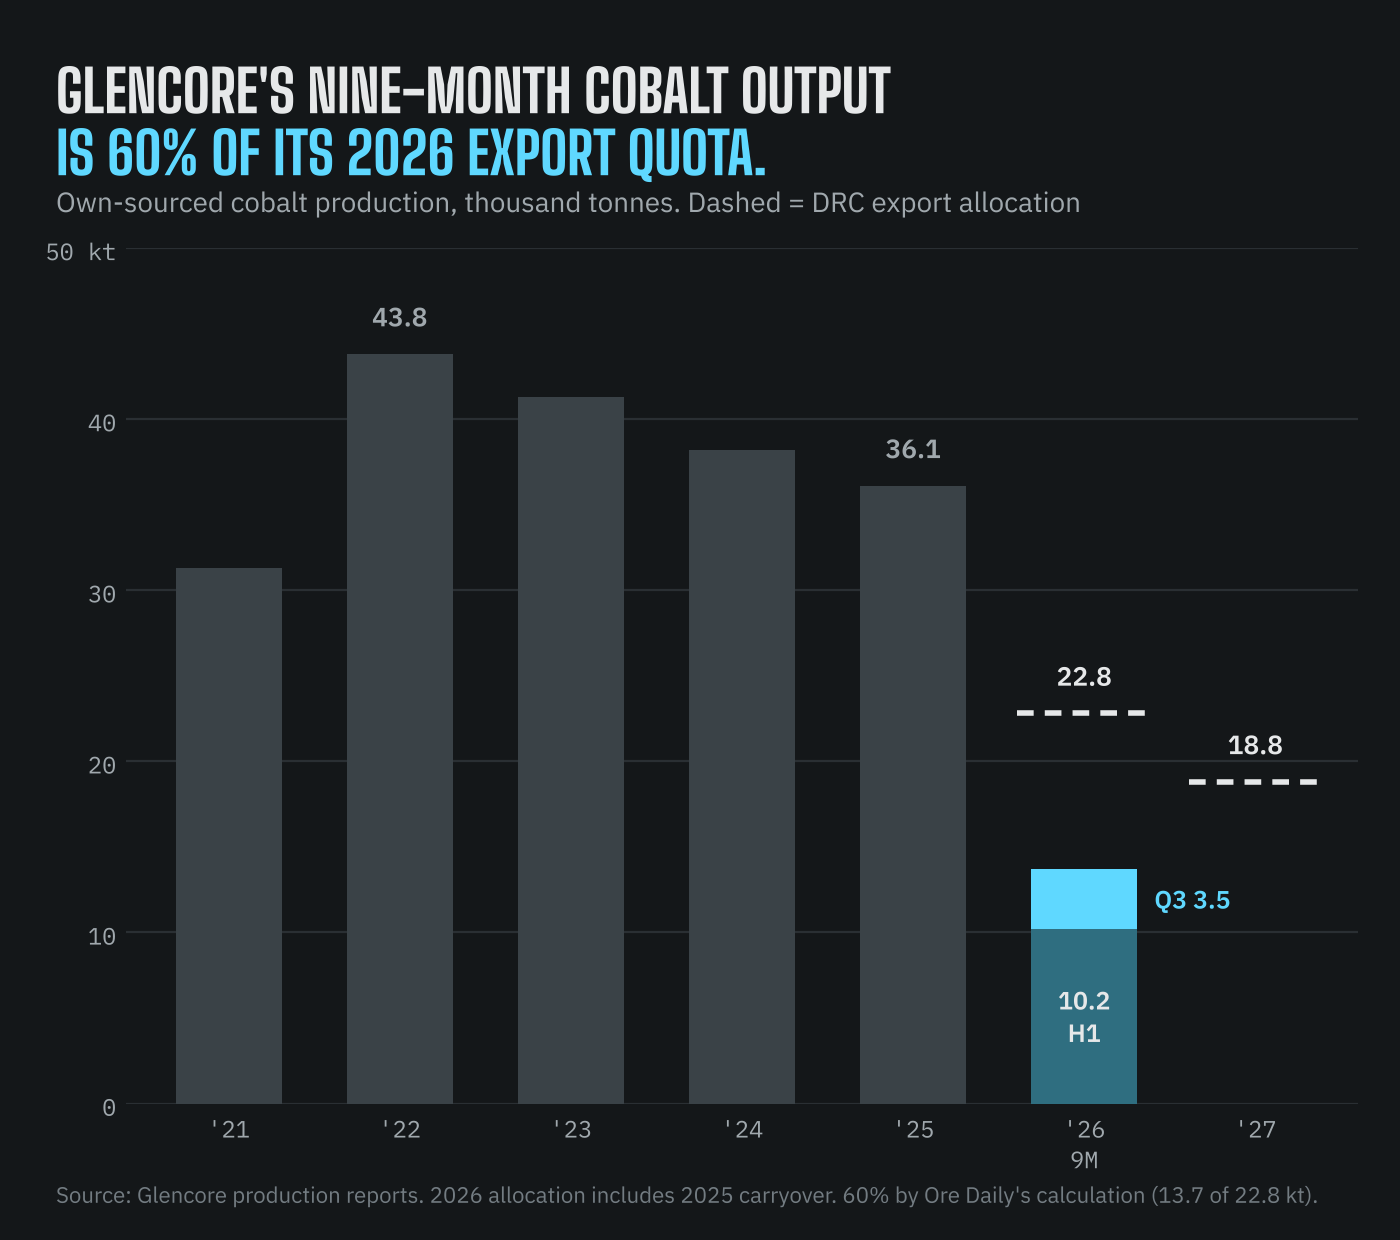
Glencore own-sourced cobalt output, 2021 to 2025, ranged from 31.3 kt to 43.8 kt and was 36.1 kt in 2025. In the first nine months of 2026 it was 13.7 kt: 10.2 kt in the first half and 3.5 kt in the third quarter. Its DRC export allocation is 22.8 kt for 2026, including 2025 carryover, and 18.8 kt for 2027.Glencore own-sourced cobalt output, 2021 to 2025, ranged from 31.3 kt to 43.8 kt and was 36.1 kt in 2025. In the first nine months of 2026 it was 13.7 kt: 10.2 kt in the first half and 3.5 kt in the third quarter. Its DRC export allocation is 22.8 kt for 2026, including 2025 carryover, and 18.8 kt for 2027.

Why output fell faster than exports

Glencore says it is putting copper first in Congo and selling cobalt from stock. Its KCC and Mutanda mines hold enough inventory to meet their quotas in the near term, the company said in January. It gave no 2026 cobalt guidance, citing too much uncertainty.

Some cobalt never shows up as output. Glencore says cobalt in mixed ore is increasingly held in solution and not dried into hydroxide. That material is not counted as production and will be processed later as rules change.

Congo replaced its export ban with quotas in October 2025. The cap is 87 kt a year for 2026 and 2027, plus a 9.6 kt state strategic quota, Glencore says. Reuters puts the total at 96.6 kt. That is about 42% of the roughly 230 kt Congo mined in 2025, based on USGS estimates, by Ore Daily's calculation. Glencore's 18.8 kt is 22% of the 87 kt company quota, the company says.

What to watch

Prices have come off the highs. Cobalt hydroxide fell 31% in the third quarter, Benchmark Mineral Intelligence said on Sept. 30. Its analyst George Ingall linked the drop to rising supply from Congo. LME cobalt still averaged $54,301/t from January to September, IMF data show, 56% above the 2025 average.

Glencore reports full-year production in late January. That will show whether it books more of the cobalt held in solution. Congo's quotas run to at least the end of 2027, Glencore says.

Sources: Glencore Q3 2026, via Discovery Alert · Investing.com, Oct 29 · Reuters via BusinessDay, Oct 29 · Glencore H1 2026 production · Glencore FY2025 production · Glencore Q3 2025 production · Glencore FY2023 production · Reuters via Mining Weekly, Dec 12, 2025 · Ecofin Agency, Oct 1 · USGS MCS 2026 · IMF PCPS, cobalt

Ore Daily analysis of public data. Figures are as reported by the sources.
2
Russia's Duma takes up a windfall-profits tax on miners today (first reading)
Bill No. 618-9 is in the 2027–29 budget package and covers companies mining ferrous and non-ferrous ores and precious-metal-bearing raw materials. The rate is 30%, or 20% for gold, and it should raise ~200bn rubles a year in 2027–29. The budget committee recommends adoption. Nornickel is widely seen as the most exposed. The Accounts Chamber (Oct 26) had criticised the lower gold rate. Russia / nickel, PGMs, gold
3
First Quantum narrows 2026 copper guidance to 405–435kt (from 405–475kt) and lifts costs sharply
Lower grades at Sentinel and Kansanshi are the cause. C1 guidance rises to $2.50–2.65/lb (from $2.15–2.40) and AISC to $4.10–4.25/lb (from $3.50–3.80), on fuel and a stronger kwacha. Q3 copper was 108,959t (+8% q/q) at C1 $2.59/lb; net earnings attributable were $207M ($0.25/sh), and net debt is $5,309M. Cobre Panama produced 13,229t from stockpiles, which last to mid-2027; a full restart still rests with President Mulino. Nickel guidance rises to 40–45kt. Zambia, Panama / copper
First Quantum can slow and still make its guide. Nine-month copper is 305.9 kt (96.5 kt and 100.5 kt in Q1 and Q2, 109.0 kt in Q3). The new 405–435 kt range needs 99–129 kt in Q4: the low end is 9% below Q3, the midpoint 5% above. The cut came off the top: Kansanshi's range moved to 175–185 kt from 175–205 kt and Sentinel's to 190–200 kt from 190–220 kt. The old 475 kt top would have needed 169 kt in Q4, 55% above Q3.
4
Agnico Eagle cuts Canadian Malartic output by up to 150,000oz a year in 2027 and 2028 after revising the Barnat pit plan
H2 2026 loses 60,000–80,000oz. Group output is now expected at the low end of 3.3–3.5Moz, with cash costs and AISC near the top of $1,020–1,120/oz and $1,400–1,550/oz. Q3 gold was 814,012oz (vs 866,936oz); net income was $1.35bn ($2.67/sh) and free cash flow $852M. Capex is unchanged at $2.6–2.8bn. This is a rare guidance miss from the sector's premium operator. Canada / gold
Agnico's low end needs no catch-up. Nine-month payable gold is 2.49 Moz (1,680,925 oz in H1 plus 814,012 oz in Q3). The 3.3 Moz low end needs 805 koz in Q4, 1% under Q3. At Q3's $4,264 realised price less $1,648 AISC, the up-to-150,000 oz cut in each of 2027 and 2028 is about $392M of margin a year, or 46% of Q3's $852M free cash flow.
5
Lynas' realised price jumps 88% to a record A$102.1/kg, lifting quarterly revenue 55% to A$310.1M
That was still 18.2% below the Visible Alpha consensus. Sales volumes fell 17.7%, while REO output rose 6.5% to 4,254t and NdPr was broadly steady. Floor-price contracts now cover more than half of production. Malaysia will shut for a month in the December quarter and Kalgoorlie for two weeks. Shares closed +4.2%. Australia, Malaysia / rare earths

Chart of the day

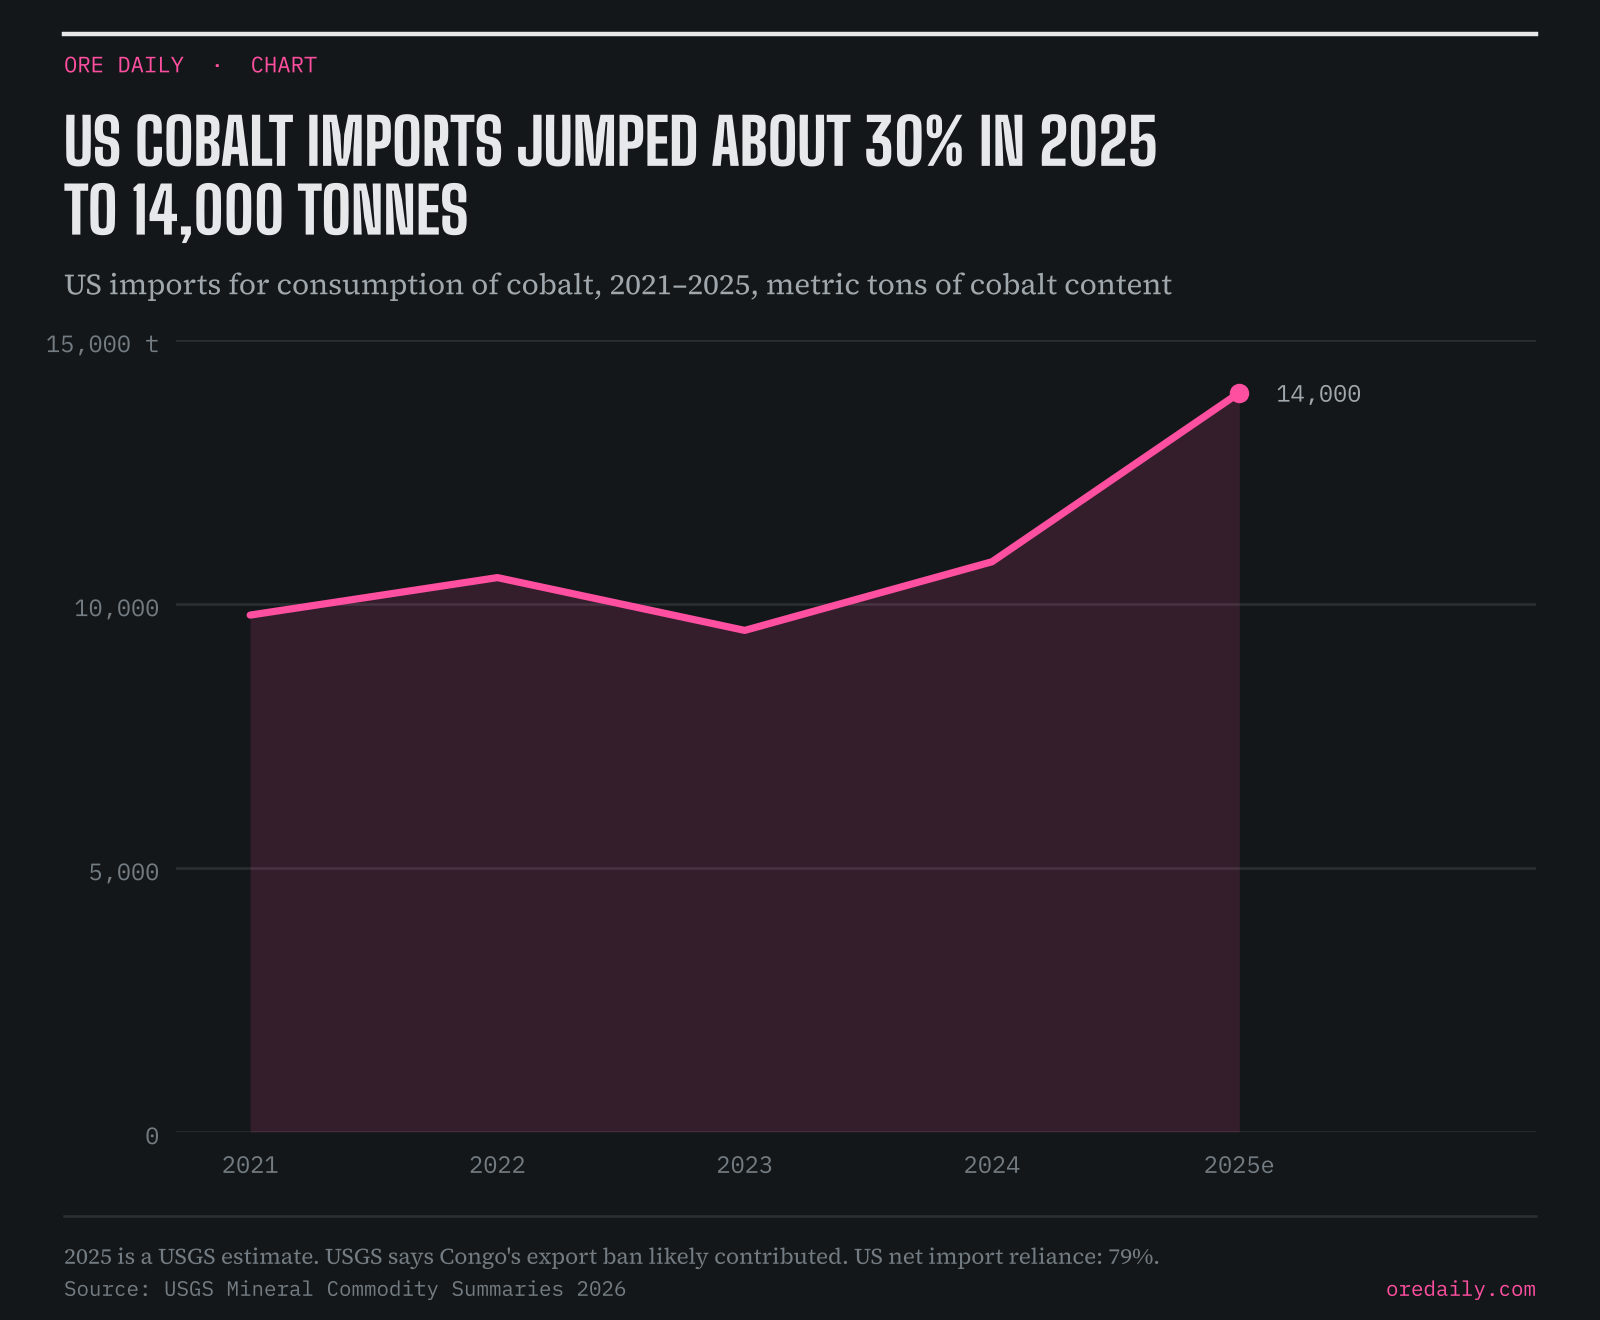
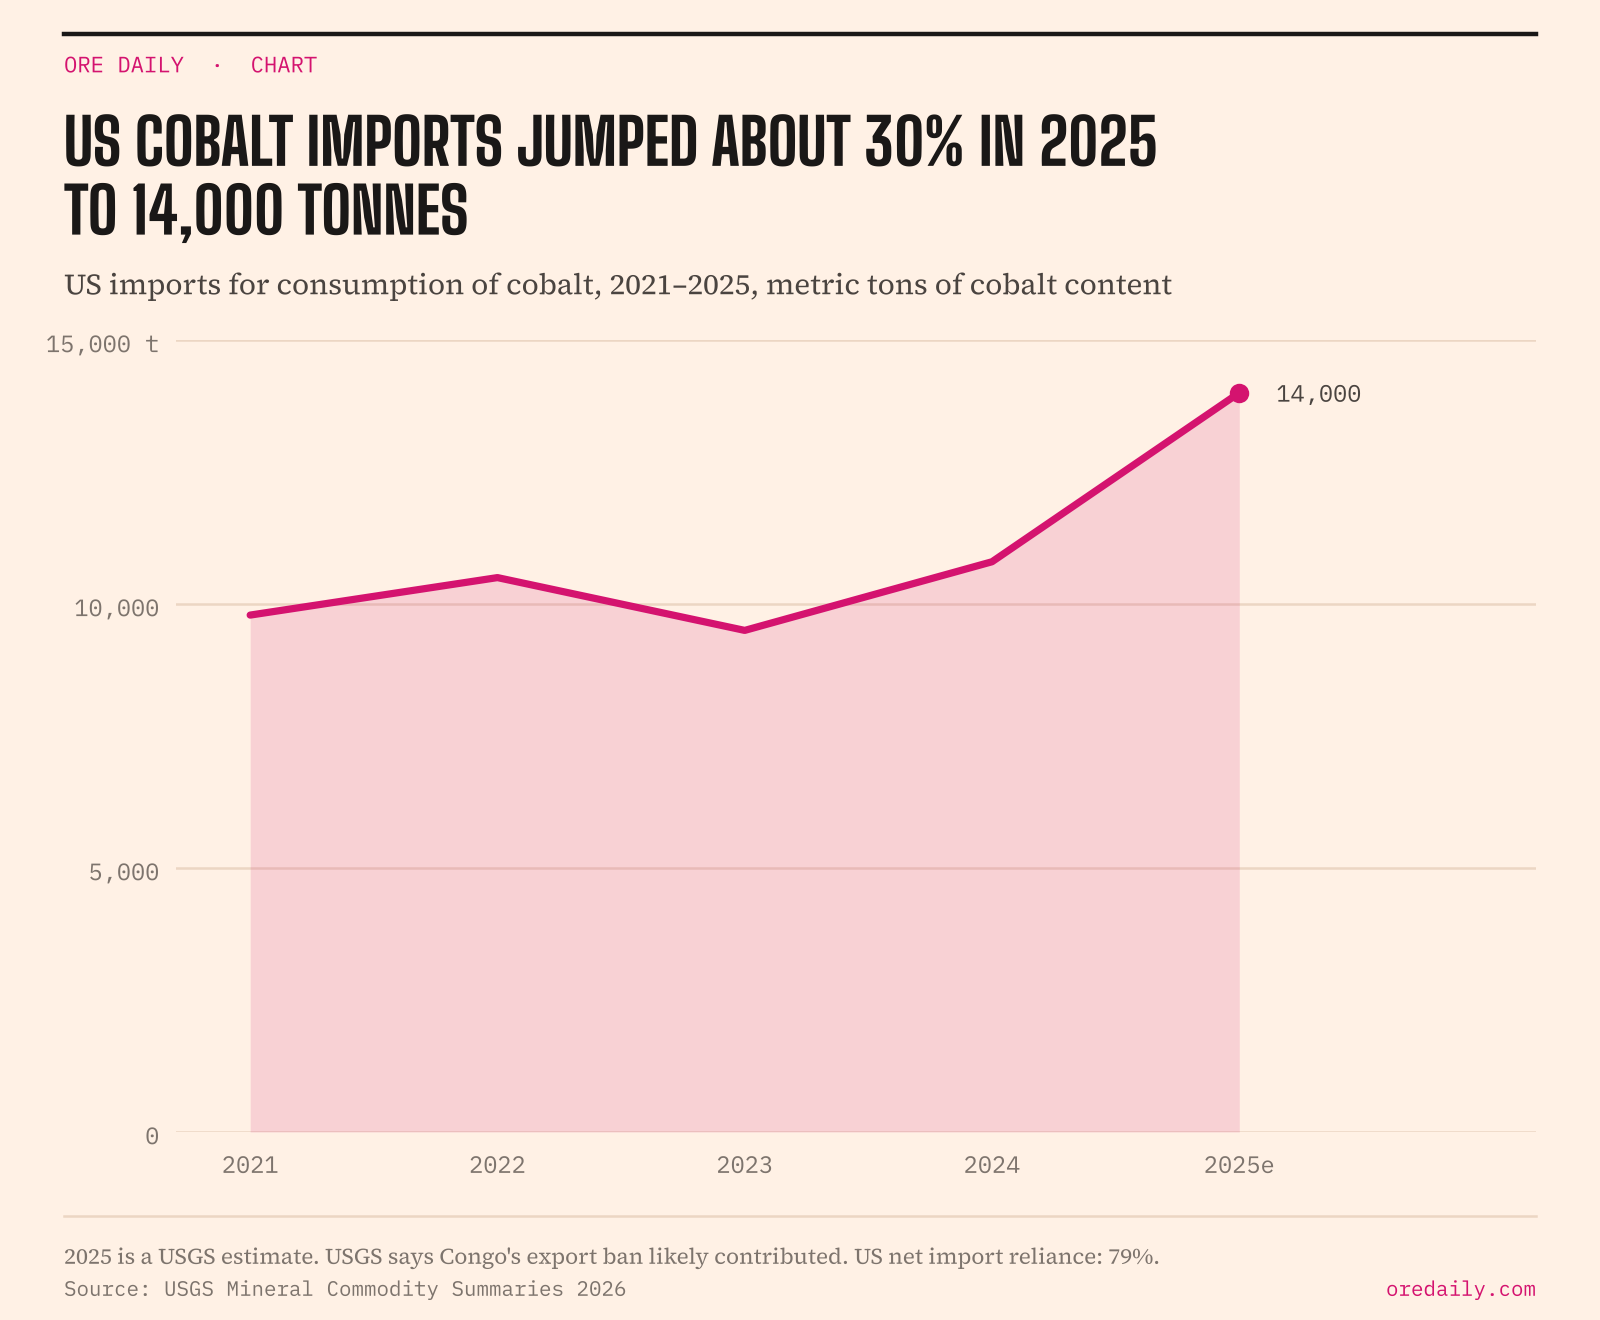
US cobalt imports jumped about 30% in 2025 to 14,000 tonnes: US imports for consumption of cobalt, 2021–2025US cobalt imports jumped about 30% in 2025 to 14,000 tonnes: US imports for consumption of cobalt, 2021–2025
US imports for consumption of cobalt rose to an estimated 14,000 t of contained cobalt in 2025 from 10,800 t in 2024, and net import reliance reached 79%; USGS says supply uncertainty after Congo's February 2025 export ban, since replaced by quotas, likely contributed. That ban and quota regime is the one Glencore blames for its 52% drop in cobalt output this year.USGS MCS 2026

Government & regulatory2

UpdateChile's Senate mining commission says Codelco reacted late to safety risks at El Teniente
Of 2,460 workers affected by the Aug 4 Andes Norte closure, ~1,800 (74%) have been relocated and 643 have no short-term option. Codelco says its safety unit now reports directly to the CEO. Sernageomin confirmed closure orders on surface work at the Cráter Norte dump over avalanche risk. This follows the Oct 11 avalanche that killed two contractors. Chile / copper
Ontario's Bill 140 (Building Ontario Faster Act, 2026)
would streamline or remove more than half of mine-related requirements and permits, the government says (first reading Oct 27, missed earlier). Canada / mining permitting

Companies & deals3

Kinross Q3: output 432,368 GEO (-17% y/y), attributable AISC $1,947/GEO (+20%)
Realised gold was $4,249/oz; net earnings $583.2M ($0.49/sh); attributable FCF $281.3M (-59%). The Sept 23 revised guidance is reaffirmed (1.84–1.86M GEO, AISC $1,850–1,900). Kinross bought back 8.2M shares for $210.1M in Q3. Round Mountain fell 27%. Global / gold
Kinross has to speed up, a little. 1,409,582 attributable GEO in nine months leaves 430–450 koz for Q4 under the 1.84–1.86M guide, 1–6% above Q3's 424,693. Nine-month AISC of $1,827 sits under the $1,850–1,900 range, so landing in it implies a costlier Q4. Q3's margin was $2,302/oz ($4,249 realised less $1,947 AISC), $314 less than Agnico's $2,616. AISC rose 20% from Q3 2025's $1,622, while the realised price rose 23%.
Glencore and CNGR commit US$20M each to Centaurus' Jaguar nickel project, with 5-year offtakes
It is conditional, including Chinese outbound approval for CNGR (announcement date not confirmed). Brazil / nickel
Central Asia Metals completed its Cygnus Metals takeover
(Oct 27, 0.06 CAML shares per share), adding the Chibougamau copper-gold project. Canada / copper, gold
Quote of the day
The floors cushion Lynas against Chinese price swings and reduce earnings volatility.
— David Tuckwell, chief investment officer, ETF Shares, on Lynas' floor-price contracts · The Edge (Reuters), Oct 29

Markets3

Gold slips after a hawkish Fed hold
the Fed held at 3.75–4.00% in a 10–2 vote, with two dissents in favour of a hike. December hike odds eased to ~78% from 84%. Spot gold was $4,037.98 (-0.7%) at 0410 GMT; Dec futures $4,049.80; silver $53.15 (-1.5%); platinum $1,515.70 (-1.5%); palladium $1,004.25 (-0.6%). Platinum and palladium are extending multi-month lows. Kedia Commodities' Ajay Kedia points to Middle East uncertainty and positioning ahead of today's PCE data.
Q4 starts $220–240/oz behind. Spot at $4,028 is $236 under Agnico's Q3 realised $4,264 and $221 under Kinross' $4,249. At Q3 AISC, that trims Agnico's margin 9% and Kinross' 10%. Spot is 11.5% below gold's 2026 average of $4,553. Kinross' cost guidance assumes $4,350 gold for the rest of 2026, 8% above spot.
Lithium carbonate reverses hard
the most-traded GFEX contract fell 8.4% to 88,360 yuan/t, through 90,000 support. Battery-grade spot was 96,100 yuan/t on Oct 29 (-3,950), after a rebound to 100,050 on Oct 28. Inventory was 128,385t (-1,894t w/w) as destocking slows.
Cobalt slides toward the "cost floor"
platform cobalt metal fell from ~230,000 to ~200,000 yuan/t over the week, while smelter ex-works held at 235,000. Sulphate is ~40,000 (cash deals 38,000–39,000) against a 42,000–43,000 production cost. Hydroxide offers are $11.5–12/lb, while overseas miners want more than $12.5. Glencore's cobalt retention (Top 5) suggests the supply squeeze is not yet showing in Chinese prices.

From X & analysts3

Yangshan premium hits "$205 per tonne," a recordRobert Friedland, Ivanhoe (X, Oct 28)
He says it is up 30% in under a week (unverified; the last logged SMM figure was $178 on Oct 26). If confirmed, it shows Chinese import demand still pulling metal even as LME stocks build.
AI "starts in the ground"Robert Friedland, Ivanhoe (X, Oct 27)
He argues US AI leadership needs control of copper for transmission and scandium for fuel cells, not just chips and capital.
Batteries are a national-security imperative; fix the "missing middle"Howard Klein (@LithiumIonBull) (X, Oct 26)
From the North American Critical Minerals Summit, he calls for sector-wide price-stability mechanisms and says seafloor nodules could mirror offshore oil's 30% share.

Drill hits6

14m @ 231.67 g/t Au New Murchison Gold (ASX: NMG), Crown Prince, Western Australia
New high-grade shoot outside the resource and below the pit shell (RC drill), hole CPRC030 from 80m, including 1m at 2,860 g/t (the average of two assays). This is one hole: neighbouring holes did not repeat the grade, coarse gold is a sampling risk, and true width is unknown (secondary summary). Gold
5.04m @ 8.72 g/t Au, 49 g/t Ag Pacifica Silver (CSE: PSIL), Claudia, Durango
~500m step-out defining a new Central Vein shoot (drill), hole 26CLAU150D from 104.63m, including 1.03m at 35.83 g/t Au, 159 g/t Ag. Combined vein strike is now >3.9km (+56%). Estimated true widths. Mexico / gold-silver
8.8m @ 2.01 g/t Au Vior Gold (TSXV: VIO), Kinebik, Quebec
First program; a previously unrecognised style of mineralisation at Florence (drill), hole KN-26-016 from 349.2m. KN-26-008 extended Florence ~80m west (2.5m at 5.32 g/t from 88m), and KN-26-002 hit 4.6m at 3.03 g/t at ~590m vertical, the deepest at Cameron Main. About 80% of samples are pending. Gold
128m @ 1.19 g/t Au Blossom Gold (TSX: BGAU), Rosebud, Nevada
Expansion hole into an unmined, sparsely drilled gap between the North and East zones (RC drill), hole RC26-012 from 181.5m, including 37.1m at 2.82 g/t. Grades are capped at 6.8 g/t. US / gold
45.5m @ 1.24 g/t Au, 0.82 g/t Ag Imperial Metals (TSX: III), Porcher Island, BC
Step-out testing the northern extension of the Christmas Tree zone (drill), hole PI-26-10 from 7.0m, including 5.0m at 5.51 g/t from 9.0m. Apparent widths only. Canada / gold
21.0m @ 1.51 g/t Au Newcore Gold (TSXV: NCAU), Enchi, Ghana
Step-out down-dip and lateral to Nyam's southern high-grade shoot (drill), hole NBDD094 from 221.0m, including 5.0m at 5.37 g/t. The headline 37m hole is infill. Gold
More exploration results on Ore PleaseDrill results ranked by g·m, every weekday›

Ongoing, no change1

No Antamina restart update; Teck Highland Valley strike continues at reduced capacity; Section 232 copper tariff undecided; no 2027 copper TC/RC settlement; no MOFCOM notice on the rare-earth control suspension; Indonesian nickel cuts unconfirmed.

Coming up, next 7 days4

Thu Oct 29
US Q3 GDP/PCE 8:30 AM ET; Teck Q3 (webcast 11:00 AM ET); Vale Q3; Implats; Russian Duma first reading on the windfall tax; EIB–Canada meeting in Montreal (to Oct 30).
Fri Oct 30
Cameco Q3; USTR Section 301 shipbuilding comments due; Chile INE output data.
Tue Nov 3
US midterms.
Thu Nov 5
Codelco EGM; Critical Metals/European Lithium implementation; IAMGOLD Q3.

Disclaimer: This content uses AI to aggregate news from public sources. Summaries may contain errors and figures are as reported by the original source. Check the linked source before relying on any item. Not investment advice.