Ore Daily BriefAgua Rica adds 0.65% of world copper from 2031. Today's stocks sit in the US.Agua Rica costs about $42,500 per annual tonne of copper. US warehouses hold 83% of visible copper stocks while China's fall. Also: what Perseus needs to make guidance, Elevra's margin returns, and drill hits in dollars a tonne.
$42.5kAgua Rica capex per annual tonne Cu$6.39bn for ~150 kt/yr
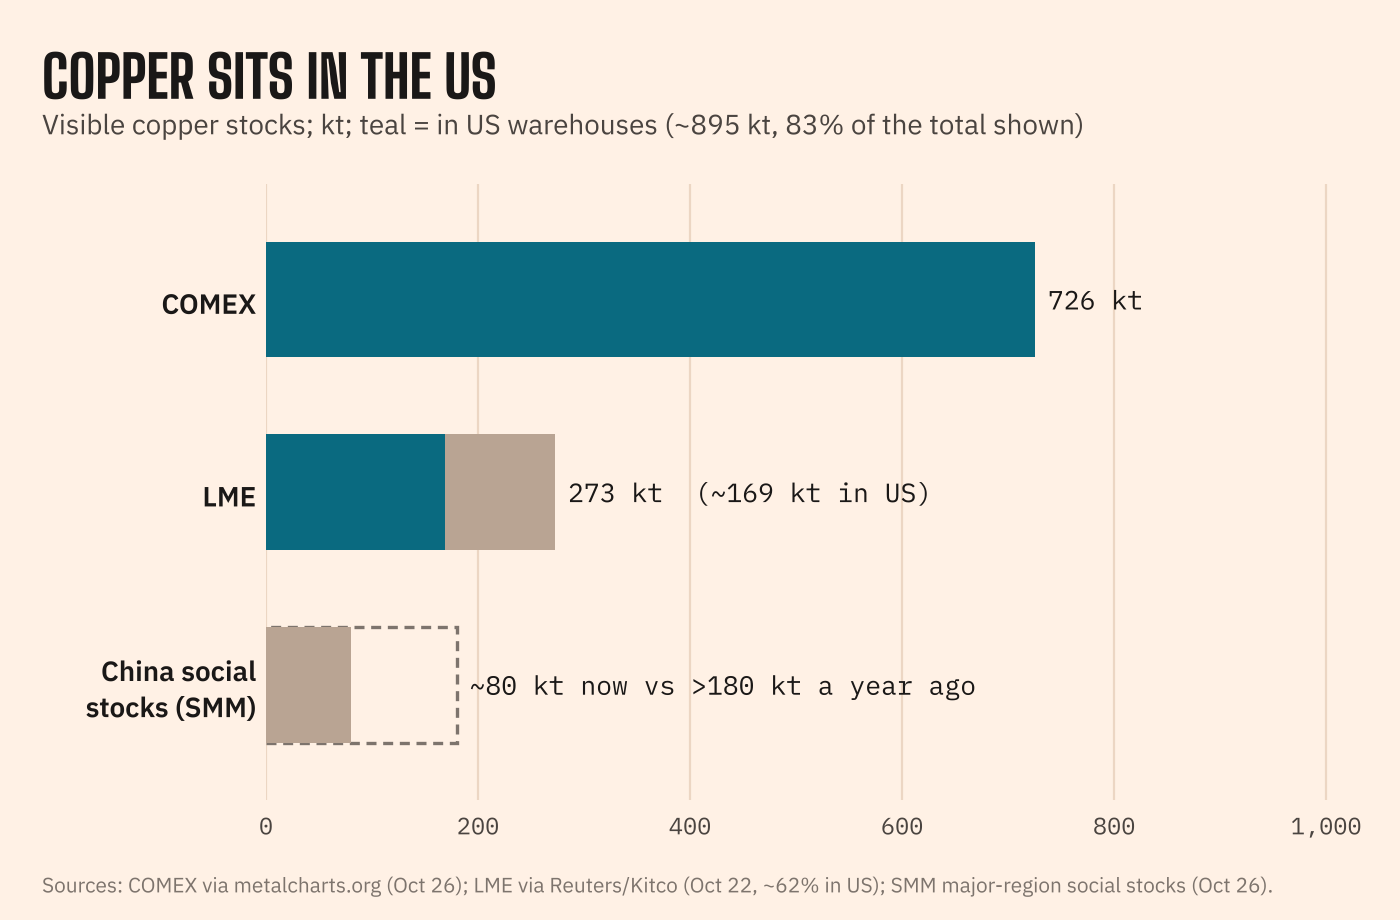
83%Visible copper stocks in US warehouses~895 kt of ~1,080 kt
$496Elevra margin per dmt, Sept qtr$14 in the June quarter
Capex intensity.$6.39bn works out to about $42,500 per annual tonne of copper, 3.4 times Cuajone's brownfield $12,400. By-products help: at today's prices copper is 81% of the value of its copper, gold and silver, and the three are worth about 9.6 times the capex.
Copper sits in the US. China's SMM social stocks of just over 80 kt are less than half a year ago. COMEX holds 725.6 kt, nine times as much, and 62% of LME stocks are in US sheds.
One drill program vs a country. Sierra Gorda's $200M over five years is $40M a year, equal to 41% of the $97M Cesco counted for all of Chile in its junior and mid-tier sample.
Precious
Perseus has to speed up. After 92,551 oz, the 420–480 koz FY27 range needs 109 to 129 koz a quarter, 18% to 40% above Q1.
Greatland in US dollars.A$2,925 AISC is about US$2,060 at 0.704, level with Perseus at $2,035. Both clear about $1,950 an ounce at $4,004 spot. Q1 annualises to 281 koz, inside guidance.
Why PGM juniors want gold. Platinum at $1,553 is 20% below its 2026 average, while gold is 12% below its own. An ounce of gold now buys 2.6 ounces of platinum.
Elk Range.290.3m @ 2.8 g/t holds about $360/t of gold in situ at spot, over 810 gram-metres. True width is not given.
FireFly.22.5m @ 1.9% Cu, 0.6 g/t Au holds about $350/t in situ at today's prices, close to Elk Range's $360/t over less than a tenth of the length. Its 2.5% CuEq uses $11,000 copper.
Ore Daily analysis of public data. Figures are as reported by the sources.
Top 5
1
Argentina approves Agua Rica for RIGI — US$6.39bn copper-gold-moly project, CatamarcaBrief
Resolution 1854/2026 (Caputo) accepts Minera Agua Rica's adhesion; 780Mt ore, ~3.46Mt Cu, 2.34Moz Au over 23 years; construction from Nov 1, 2027, operations Oct 2031.One of the largest RIGI mining approvals yet, and it locks in 30-year fiscal terms for a long-delayed project.
US and Canada working on deal to ease Section 232 steel and auto tariffs (Reuters exclusive, Oct 27)
Talks cover Section 232 duties of up to 50% on Canadian steel and 25% on autos; Trump has announced both rising to 50% from Jan 1, 2027.No terms are confirmed, and aluminium is not mentioned. A Canadian industry source expects a "narrowed deal, if it even happens." US midterms are Nov 3.
Lula's win puts Brazil's rare earths in Washington's sightsPerspective
Brazil holds the second-largest RE reserves (USGS 21Mt); 42% of 2,727 RE exploration applications are foreign; USA Rare Earth (10% US-government owned) now owns Serra Verde.Lawyers expect more screening and local-processing demands but a predictable regime. Lula takes office Jan 5, 2027.
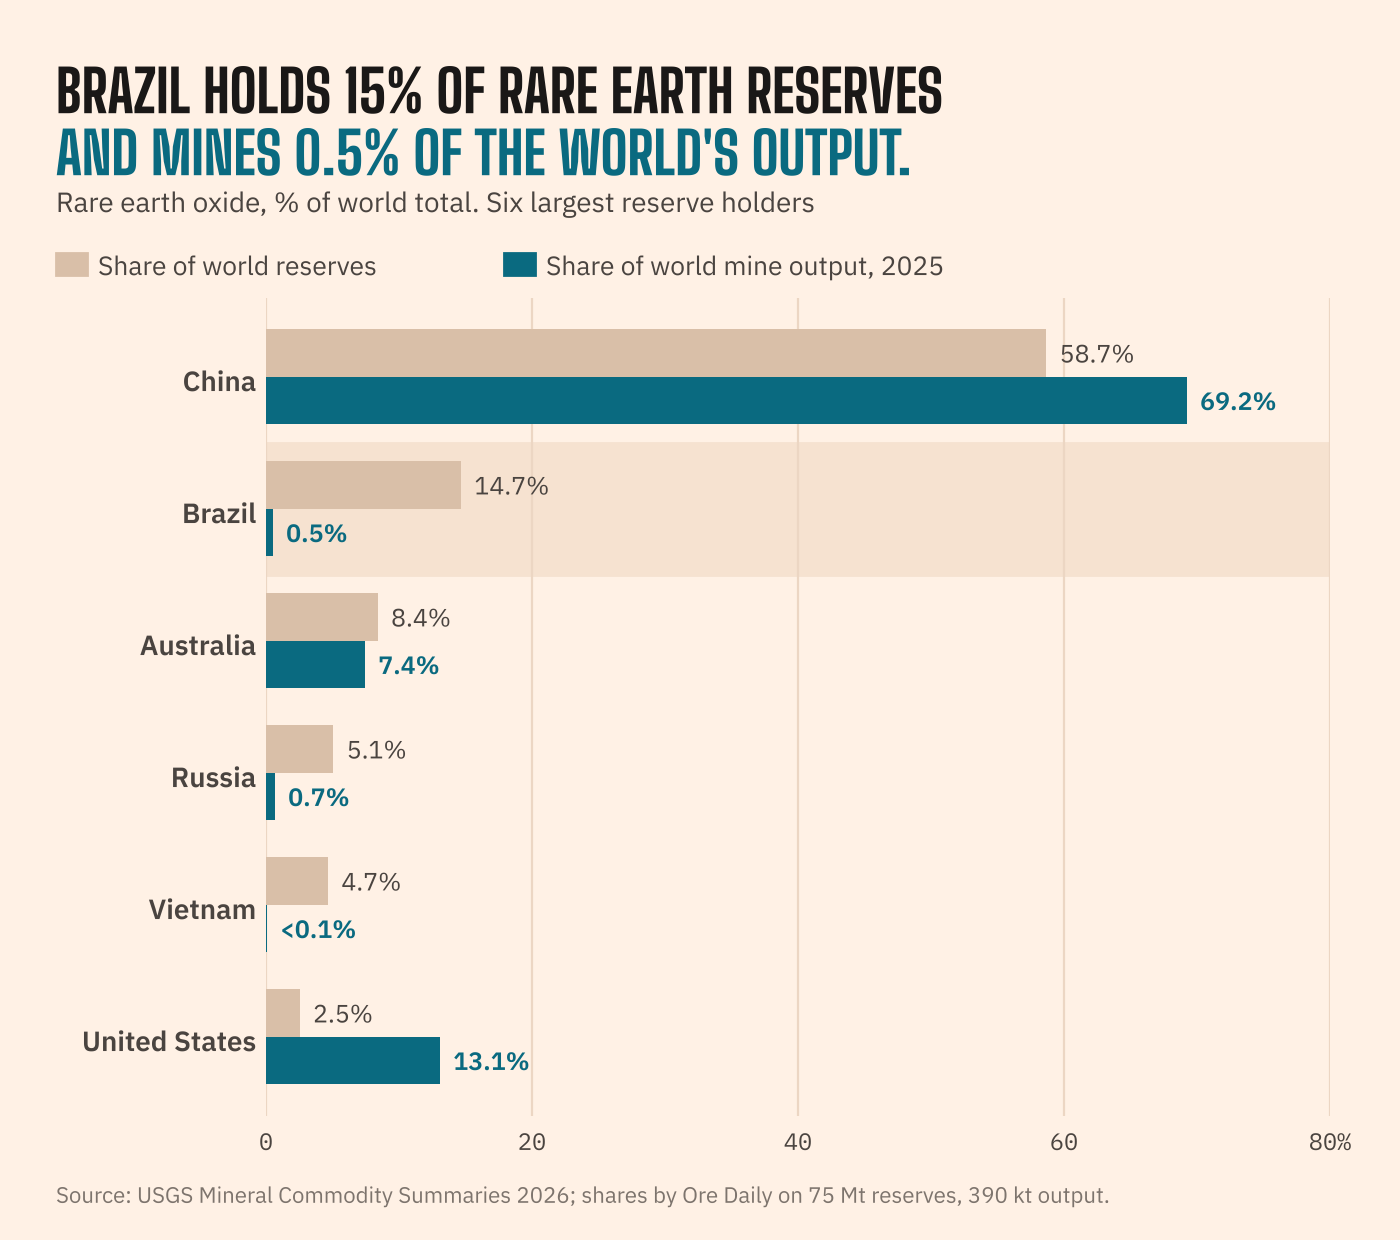
Ore Daily PerspectiveBrazil holds 15% of rare earth reserves and mines 0.5% of output
Brazil ranks second to China for reserves. It ranks ninth for output. One mine, now US-owned, makes all of it.
5,500 yrsBrazil's reserves at its 2025 mine rateChina: 163 years
11 MtBrazil reserves, USGS 2026Cut from 21 Mt
2,000 tBrazil mine output, 2025eOf 390,000 t world
The numbers
USGS puts Brazil's rare earth reserves at 11 Mt of oxide in its 2026 Mineral Commodity Summaries. That is down from 21 Mt in earlier editions, after Brazil's mining agency ANM revised its figures. MINING.COM's report still cites 21 Mt. On the new figure Brazil is still second to China, with about 15% of the world's 75 Mt-plus.
Output is small. Brazil mined about 2,000 t in 2025, up from 560 t in 2024, USGS estimates. That is 0.5% of the 390,000 t world total. At that pace its reserves would last 5,500 years, by Ore Daily's calculation. China's would last 163 years and the world's about 190.
One mine
All of it comes from Serra Verde's Pela Ema ionic clay operation in Goiás, which started in January 2024. USA Rare Earth closed its takeover on Sept. 3. The Brazilian observatory OBM put the equity value at about $2.8bn. MINING.COM reports the US government owns 10% of the buyer.
The company targets a run-rate of about 4,000 t a year by end-2026, then 6,400 t once Stage 2 runs. That is double and then triple Brazil's 2025 output. At 6,400 t, Serra Verde alone would be about 1.6% of 2025 world output, by Ore Daily's calculation. A US-backed vehicle buys all Phase 1 output under a 15-year offtake, with price floors for dysprosium and terbium.
The pipeline is crowded. ANM records 2,727 rare earth exploration applications through June. Foreign-owned firms filed 42%, or about 1,145, and more than 86% came in the past three years, MINING.COM reports. OBM says the next projects reach production between 2028 and 2030.
What to watch
China's one-year pause of its October 2025 export controls expires Nov. 10. Lula starts his new term on Jan. 5, 2027. MINING.COM reports Brazil's September critical minerals policy gives the state more say over control changes and supply deals. Mattos Filho's Adriano Drummond Trindade told MINING.COM investors accept screening if it is predictable.
Ore Daily analysis of public data. Figures are as reported by the sources.
5
China physical copper keeps tighteningBrief
SMM puts major-region social stocks at just over 80,000t, down ~20,000t w/w and >100,000t below a year ago, as typhoons delay import vessels.Yangshan premium $178/t (+$10). LME 3M closed $14,338 (+0.28%) Monday.
Copper sits in the US. China's SMM social stocks of just over 80 kt are less than half a year ago. COMEX holds 725.6 kt, nine times as much, and 62% of LME stocks are in US sheds.
Government & regulatory8
EU weighs direct equity stakes in critical-minerals projects
Last week MEPs backed a Critical Raw Materials Centre that could invest in companies, stockpile and monitor supply, with €2bn under the next EU budget; it is partly modelled on Japan's JOGMEC.Lead MEP Mohammed Chahim says €2bn is not enough. Member states must still approve. This moves the EU toward the US equity-stake model (MP Materials). EU
Minister Chang Lih Kang told parliament that 1.45Mt of 1.467Mt of WLP residue has been moved to the permanent disposal facility.Lynas must stop generating WLP waste by March 2031 or the regulator may suspend its licence. Malaysia / rare earths
BHP can spend up to US$40M on geophysics, studies and drilling over a 24,000ha early-stage property.Signed Oct 21 during LME Week; first reported Oct 26. This is a rare Codelco opening of its 2.3Mha land bank to a major. Chile / copper
Chile SEIA: Sierra Gorda SCM files a DIA for Catabela NoresteBrief
The campaign covers 174 drill platforms to ~1,500m, ~US$200M, 2028–2032.Filing starts review only (filed Oct 20, not previously reported). Chile / copper
One drill program vs a country. Sierra Gorda's $200M over five years is $40M a year, equal to 41% of the $97M Cesco counted for all of Chile in its junior and mid-tier sample.
Chile exploration is thin: Cesco PIEx 2026 counts 22 active projects and only US$97M invested
(90 companies surveyed), mostly early reconnaissance.Chile / copper
NSW Critical Minerals Skills Plan; King and Houssos launched the NextGenMIN hub (UNSW); MACH Mount Pleasant keeps its permanent workforce to 2032 under a legislated deal; Sunrise Syerston scandium was showcased.Australia
South Africa: presidency told ex-Sibanye CEO Froneman to leave B4SA
after he said officials behind Iran, BEE and expropriation policies should face US sanctions.B4SA chair Kingston says he spoke for himself. SA elections are under three weeks away. South Africa
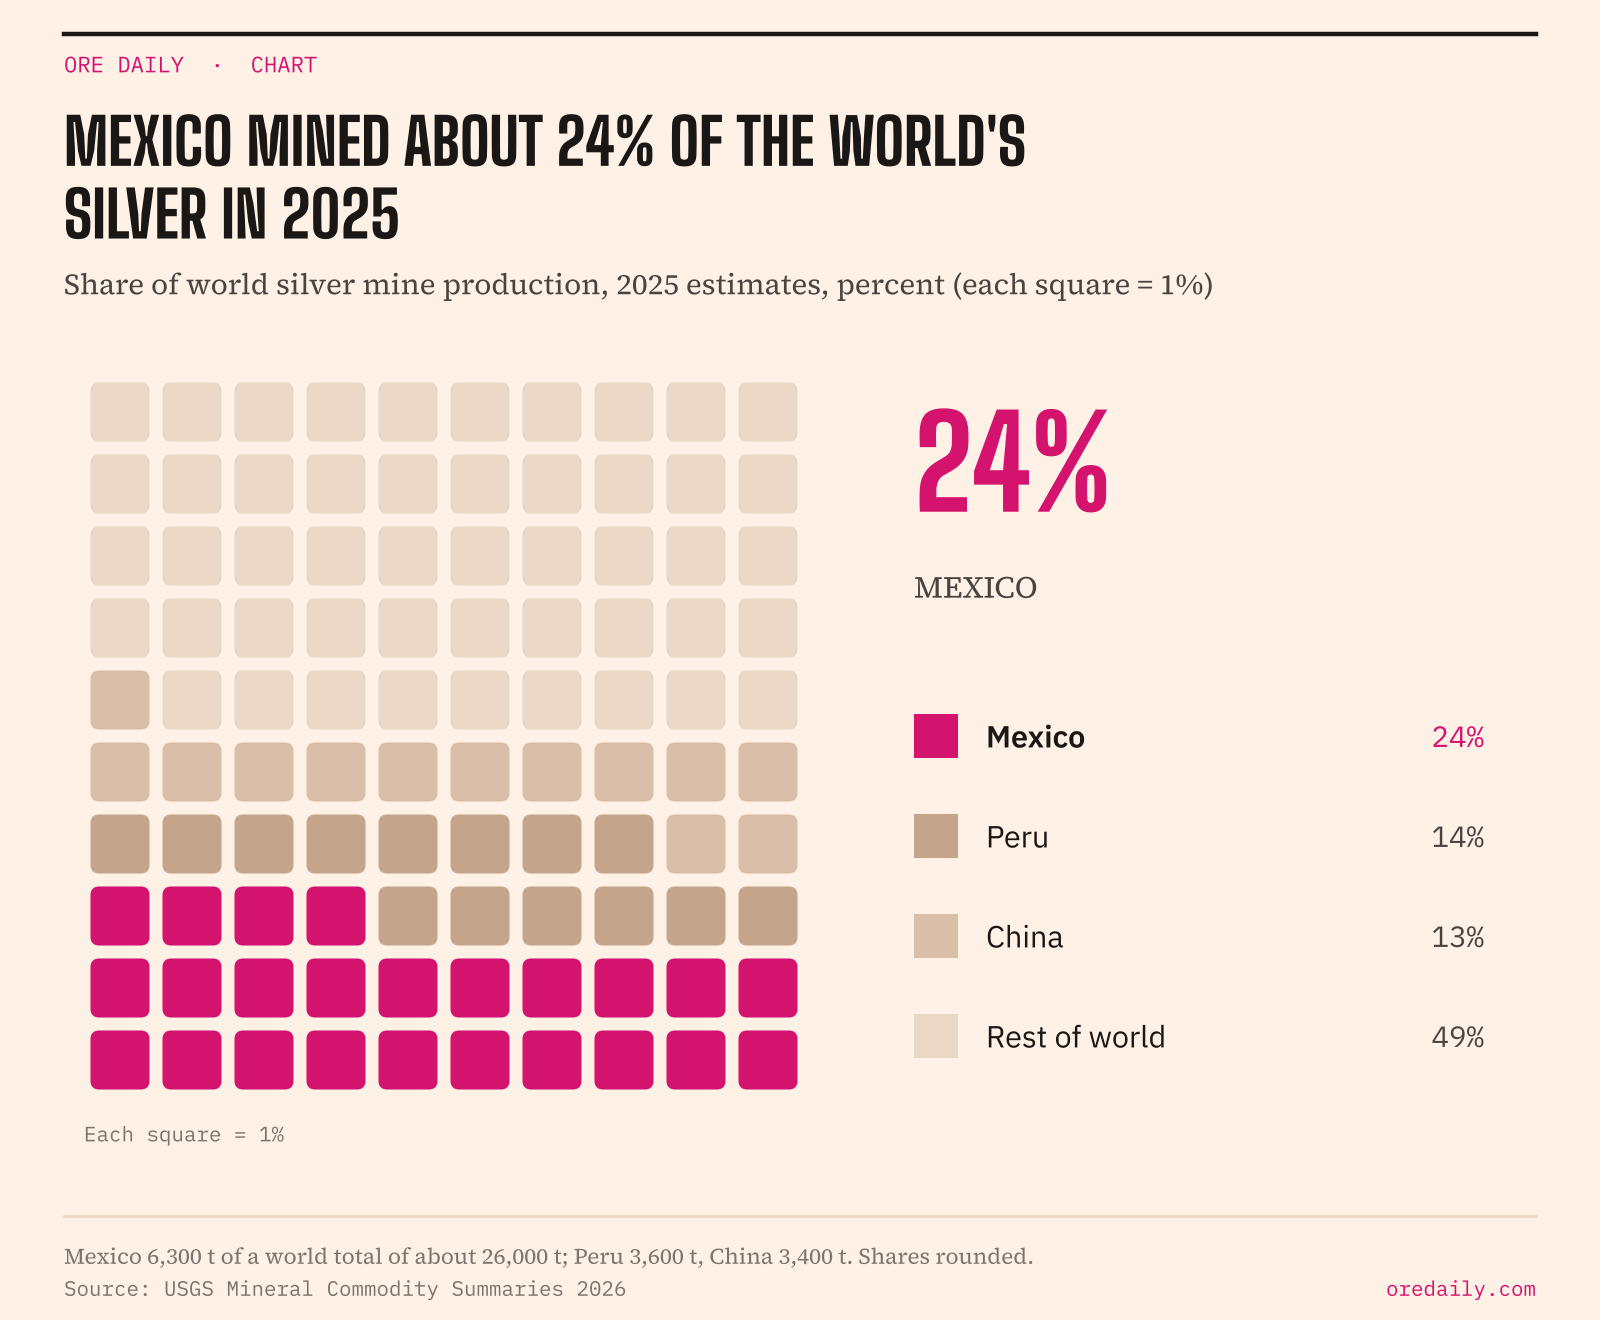
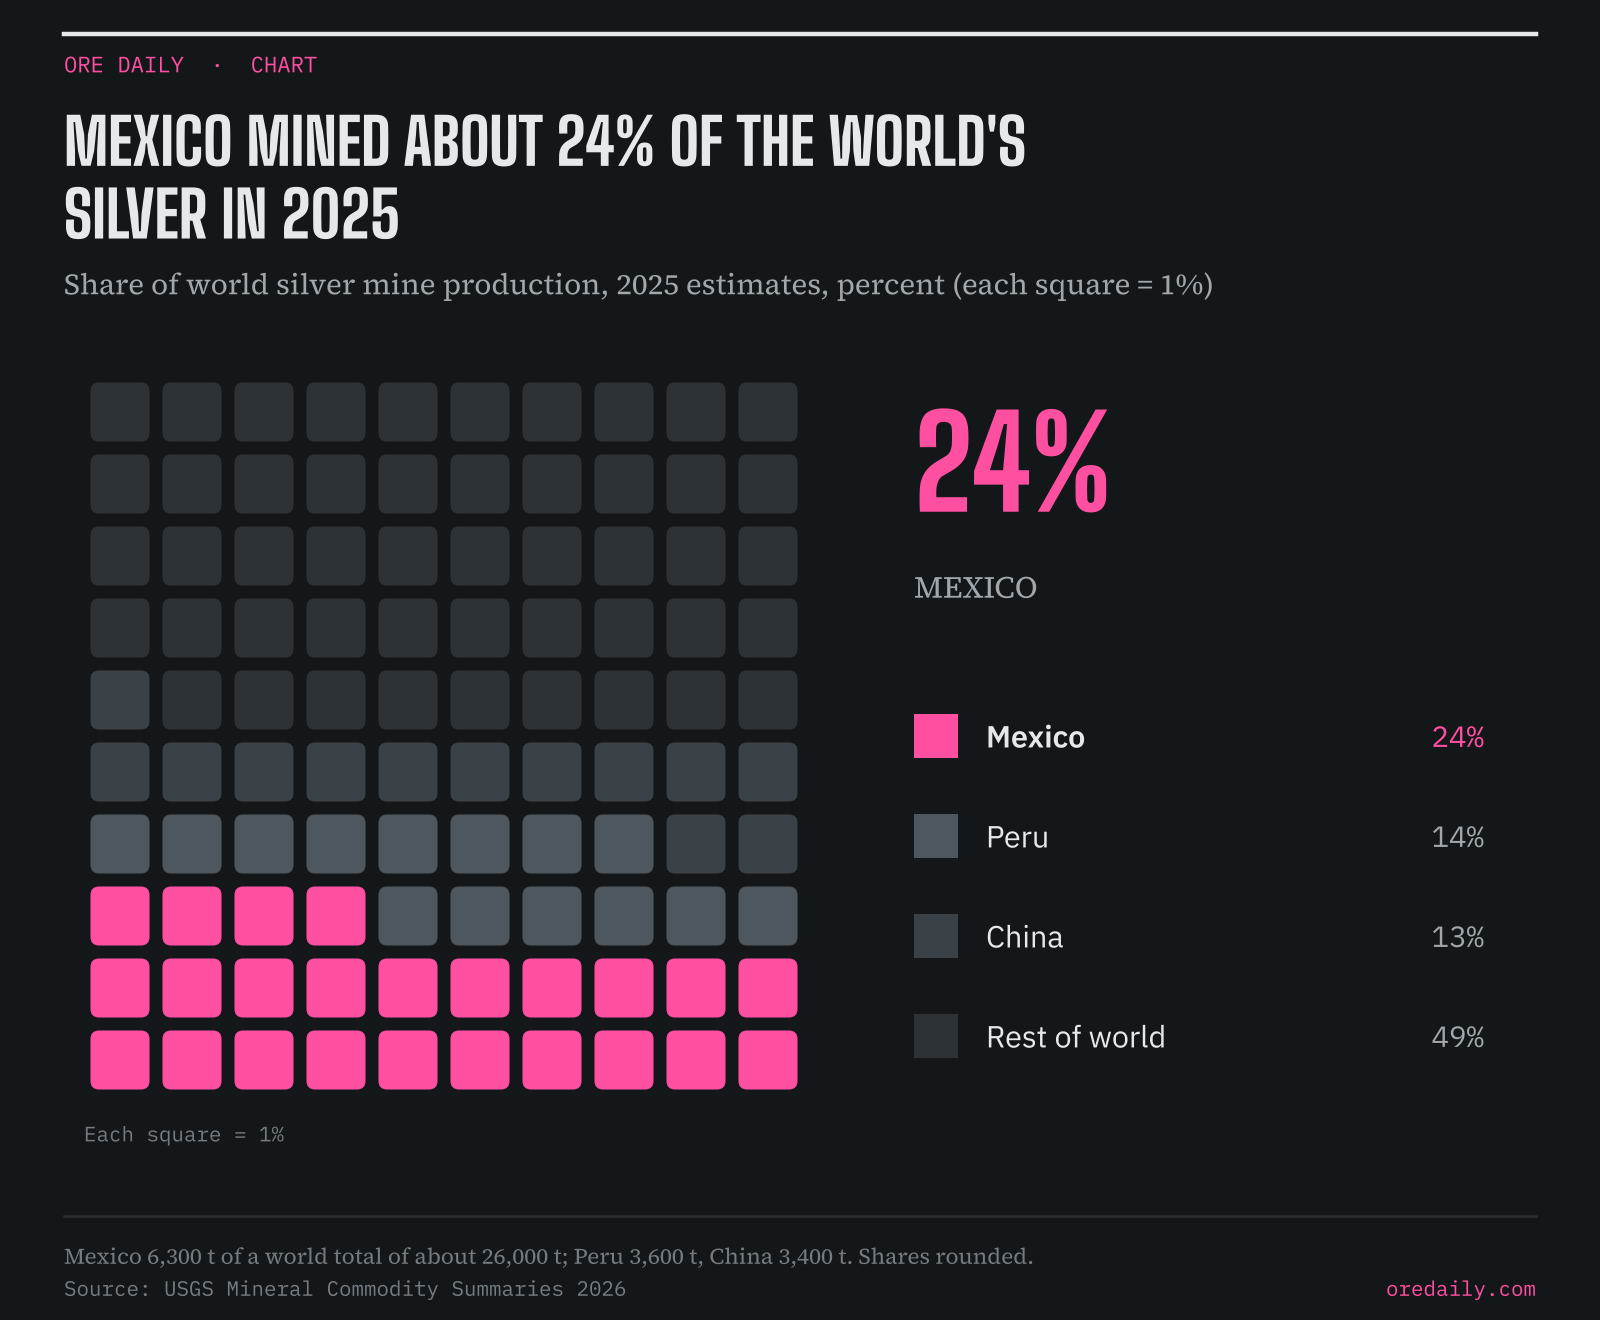
Mexico mined an estimated 6,300 t of silver in 2025 out of a world total of about 26,000 t, ahead of Peru (3,600 t) and China (3,400 t); Mexico also supplied 47% of US silver imports in 2021–24. The backdrop to Fresnillo's 11.5% y/y drop in nine-month attributable silver output.USGS MCS 2026
Production & trade data2
China industrial profits: Jan–Sep +15.5% y/y to 6.03trn yuan; September +14.4%
Mining-sector profits rose 38.2% Jan–Sep, versus manufacturing +17.0%.Higher metal and energy prices are carrying upstream earnings. China
UpdateTeck Highland Valley strike involves 1,277 USW 7619 members
(vs ~1,200 cited earlier).The mine runs at reduced capacity and Teck has not revised its outlook. The contract expired Sept 30; talks broke down Oct 8. Evolve Royalties (0.51% NPI) flagged exposure. Teck Q3 is Oct 29. Canada / copper
concentrate 54,907 dmt at 5.1%; sales 58,134 dmt (+71% q/q); realised US$1,276/dmt (provisional); unit cost US$780/dmt (-14%); net cash US$240M.Sale of its Ewoyaa interest to Huayou completed Oct 26 for ~US$71M. Canada/Ghana / lithium
Greatland in US dollars.A$2,925 AISC is about US$2,060 at 0.704, level with Perseus at $2,035. Both clear about $1,950 an ounce at $4,004 spot. Q1 annualises to 281 koz, inside guidance.
PTM's smaller Waterberg "T-Zone" plan lifts gold to ~19% of output (from 5%); Southern Palladium's milling change could triple Bengwenyama chrome to 1Mtpa, raising post-tax NPV to $1.96bn.Valterra agreed to buy half of Tharisa's PGM concentrate for five years. South Africa / PGMs
Why PGM juniors want gold. Platinum at $1,553 is 20% below its 2026 average, while gold is 12% below its own. An ounce of gold now buys 2.6 ounces of platinum.
Missed last week: Fresnillo Q3 attributable silver 10.3Moz
(-11.6% y/y; 9M 32.4Moz, -11.5%).Juanicipio fell 26% to 1.8Moz; 9.6Moz is needed in Q4 to reach the low end of 42.0–46.5Moz guidance. Gold 135,100oz (-11%). Mexico / silver
Missed last week: US-backed Orion CMC nears close on stakes in Glencore's DRC copper-cobalt mines
(Bloomberg, Oct 23).The Feb preliminary deal was for 40% of Glencore's interests in two operations; Orion CMC targets a $5bn pool. Its CEO says the US may buy and store copper if tariffs aren't imposed. DRC / copper-cobalt
spot gold $4,003.59 (-0.3%) and silver $53.06 (-1.6%) in Asia Tuesday, after Monday's recovery above $4,000 as Brent eased to $115.81.Fed decision Wed 2:00 PM ET.
FireFly Metals — new greenfields VMS discovery at Mount Joy (drill)Brief
FFR26-071: 22.5m at 1.9% Cu, 0.6g/t Au (2.5% CuEq) from 109m, including 9.0m at 2.9% Cu.FFR26-076 shows ~40m of semi-massive sulphides (visual only, assays ~4 weeks). Site is 2.6km from the Nugget Pond mill; this is FireFly's first program in the Tilt Cove district. Newfoundland / Cu-Au
FireFly.22.5m @ 1.9% Cu, 0.6 g/t Au holds about $350/t in situ at today's prices, close to Elk Range's $360/t over less than a tenth of the length. Its 2.5% CuEq uses $11,000 copper.
Elk Range Mining — maiden hole at Friday (drill)Brief
26FRD001: 290.3m at 2.8g/t Au from 18.7m, including 89.6m at 5.5g/t; shares +48% pre-open.True width not given. Idaho / gold
Elk Range.290.3m @ 2.8 g/t holds about $360/t of gold in situ at spot, over 810 gram-metres. True width is not given.
Rocky Shore Gold — new MTH zone east of Mosquito (drill)
MH-26-06: 50.0m at 1.01g/t; MH-26-08: 144.4m at 0.34g/t, including 48.9m at 0.73g/t.Previously undrilled; traced >400m east, open in all directions. Gold Anchor, Newfoundland / gold
Gold managed-money net long fell for an eighth week, -9.0t to 324t (lowest since May 26).Silver net long fell 38% to 545t (lowest since Feb 2024). She sees a silver surplus of ~7 weeks of fabrication demand (~11 with ETP selling) and cites Russian official-sector selling and Kazakh offloading. Gold support $3,940.
@robert_ivanhoe (Robert Friedland, Ivanhoe) — premiums and TC/RCs (X, Oct 26)
He cites China cathode premiums of $158–178/t and spot TC/RCs at -$300/-30¢, with a possible 2027 benchmark near -$150/15¢ (TC/RC figures unverified).The $178 Yangshan figure matches SMM via SP Angel.
@robert_ivanhoe — Payne Institute copper gap (X, Oct 26)
Cites Payne Institute (Colorado School of Mines): 16.1Mt/yr of new mine supply needed by 2050 at ≥$360bn.That is above BNEF's $332bn estimate from last week.
China Oct-2025 RE controls suspension expires Nov 10
still no MOFCOM notice; the export-control bureau's latest posting is Oct 19.Section 232 copper still undecided. Indonesian nickel cuts still unconfirmed. Codelco EGM Nov 5.
Coming up, next 7 days5
Tue Oct 27
Freeport Q3; FOMC day 1; IMARC continues (to Oct 29).
Wed Oct 28
Fed decision 2:00 PM ET, Warsh presser 2:30 PM ET; Agnico, Kinross, First Quantum Q3; Brazil PlanGeo consultation closes.
Thu Oct 29
US Q3 GDP and Sept PCE 8:30 AM ET; Teck, Glencore, Vale, Lynas, Implats results; EIB–Canada Montreal (to Oct 30).
Fri Oct 30
Cameco Q3; USTR Section 301 shipbuilding-suspension comments due; Chile INE output data (~Oct 30); Kishan Reddy's Australia visit ends.
Tue Nov 3
US midterms. Thu Nov 5: Codelco EGM; Critical Metals/European Lithium scheme implementation; IAMGOLD Q3.
Disclaimer: This content uses AI to aggregate news from public sources. Summaries may contain errors and figures are as reported by the original source. Check the linked source before relying on any item. Not investment advice.