Top 5
1Newmont Q3: output down, costs guided lower, out of Northern Star race
Attributable gold 1,302koz (1.42Moz a year earlier, per Reuters); AISC $1,454/oz by-product; FCF $1,912M; 2026 output held at 5,260koz with AISC guide cut to $1,520/oz. Viljoen says Newmont is not bidding for Northern Star, which narrows the field for NST assets.
2Red Chris block cave gets its first price tag: $4.2–4.8bn
Newmont 70% / Imperial 30%; real terms, 100% basis, net of the C$500M federal contribution. Full-funds decision early 2027, first production 2033, first 13-yr cave ~3.0Moz Au and >1.8bn lb Cu. Q3 Red Chris Cu 14.771M lb (−29% y/y). Gives a capex anchor for one of Canada's largest new Cu-Au sources. BC/copper-gold.
3Copper at 5-week low as US stocks flow back to LME
LME 3M $14,089 (−1.8%) at 1600 GMT, low $14,031. LME stocks 272,950t, highest since Jul 24, after 29,050t of inflows (mostly New Orleans); ~62% of LME copper is now in US sheds. Marex says the front of COMEX has flipped to a discount to LME, so the tariff-arbitrage overhang is unwinding.
4Ghana puts Gold Fields' Tarkwa tenure in play
Leases expire in April. Officials have weighed handing it to local owners, though the minister says seizing foreign mines is not policy. E&P (owned by the president's brother) is claiming >$700M from Gold Fields in arbitration. The revised mining law is due by year-end, with shorter leases and an end to stability agreements. Ghana/gold.
5MinRes Q1 FY27: record lithium sales, but realised price down 23% q/q
166k dmt SC6 attributable (+17% q/q), 170k dmt sold, US$1,873/dmt CIF. Onslow shipped 9.2M wmt (~36.9Mtpa run-rate). Diesel at ~A$1.60/L vs the A$1.25/L in guidance will hit October costs. It is the first big Australian lithium quarterly to show price falling even as volumes set records.
Government & regulatory12
US Commerce: $389M in letters of intent for equity stakes, including high-purity quartz
From the CHIPS R&D programme, for minority non-voting stakes: Sibelco $56M for ultra-high-purity quartz purification; Vertical Semiconductor $73M for vertical GaN; Helion $175M; CFS $85M. These are preliminary, not final. The equity-for-funding model is reaching materials. US.
Section 232 wind-turbine proclamation: no new tariff yet
Orders Commerce and USTR to negotiate and report within 180 days. Confirms that the steel, aluminium and copper 232 duties (Proc. 10962) already apply to turbine parts. Does not mention magnets. US/Cu-Al-steel.
China Announcement No. 52 (missed Oct 19): customs "challenge" procedure for dual-use exports
Effective Oct 19. Customs holds goods with no licence shown; exporters have 7 working days to respond; customs and then MOFCOM each get 15 working days; complex cases have no time limit. Covers e-commerce and express shipments. This can slow clearance of minor metals whatever happens to the Nov 10 suspension. Under-reported.
Yukon: Boroo to buy Victoria Gold's Eagle mine out of receivership for up to C$140M
C$40M upfront plus C$100M on permitting and production milestones; ~C$800M planned spend 2027–29 on remediation and a phased restart; framework agreement with Yukon. Court approval early Dec, close ~Dec 31. It is the first route to cleaning up and restarting the site after the 2024 heap-leach failure.
Ghana: contract-miner pay rules due Nov 30
The Lands Ministry told the Minerals Commission to propose wage protections. Surface contract mining is reserved for Ghanaian firms and underground partnerships must be ≥50% Ghanaian; compliance by end-Dec. This adds local-content pressure on top of the Tarkwa issue.
Chile: QB2 pit expansion gets environmental approval (RCA No. 20269900138)
US$141M: larger pit, higher mining rates, dewatering, trucked concentrate, more extraction at Cantera 5. Published in the Diario Oficial Oct 20; 30-day appeal window. It underpins Teck's QB2 debottlenecking. Under-reported.
Brazil: decree staffs the critical minerals council (CIMCE); ANM warns of overlapping powers
3 sub-secretariats and 23 posts. ANM DG Mauro Sousa says the implementing rules must split roles to avoid investor uncertainty. Comes days before the Oct 25 runoff.
Brazil: federal court suspends all licences for Herculano's Serro iron ore project (MG)
~1Mtpa, R$300M capex; the court cited historical heritage. Small tonnage, but it shows judicial licence risk.
Thailand proposes import ban on copper, aluminium and ferrous scrap
Customs proposal of Oct 21 covering HS 7204/7404/7602/4004, with a 6–12 month transition and tighter container checks. No effective date yet. Thailand is a processing hub that feeds Chinese scrap supply. Single-source (SMM).
India licenses ~6,500t of silver imports over six months (Reuters, dealers)
Import duty on gold and silver was raised from 6% to 15%; local premiums fell to $0.45/oz from up to $2.50. Dealers call it far more than India needs, which hangs over a falling silver market.
Zambia: ZCCM-IH moves to buy small-scale gold for the central bank
It cites ~US$1.8bn of UAE gold imports from Zambia in 2023 vs ~127koz of formal output. Purchases via Kyalo Goldfields in kwacha, modelled on Ghana's GoldBod.
UpdatePeru: Minister Shinno says Reinfo ends Dec 31 with no extension; then an 18-month simplified path
Oversight moves to the national government; a census of small-scale miners is planned via INEI.
Production & trade data3
Peru Jan–Aug mining exports US$57.5bn (+55%)
Copper $26,513M (+54.8%), gold $21,631M (+58%). August copper exports $3,679M (+56%) on price +38.1% and volume +13%; a rare volume gain in the Andes. SNMPE.
China resumes sulphuric acid exports to Chile after a 3-month gap
September: 31,666t, 93.5% of China's 33,873t total acid exports (which were −92.13% y/y). Chile uses ~8.2Mtpa, ~48% imported, so this is a token volume for SX-EW cathode producers.
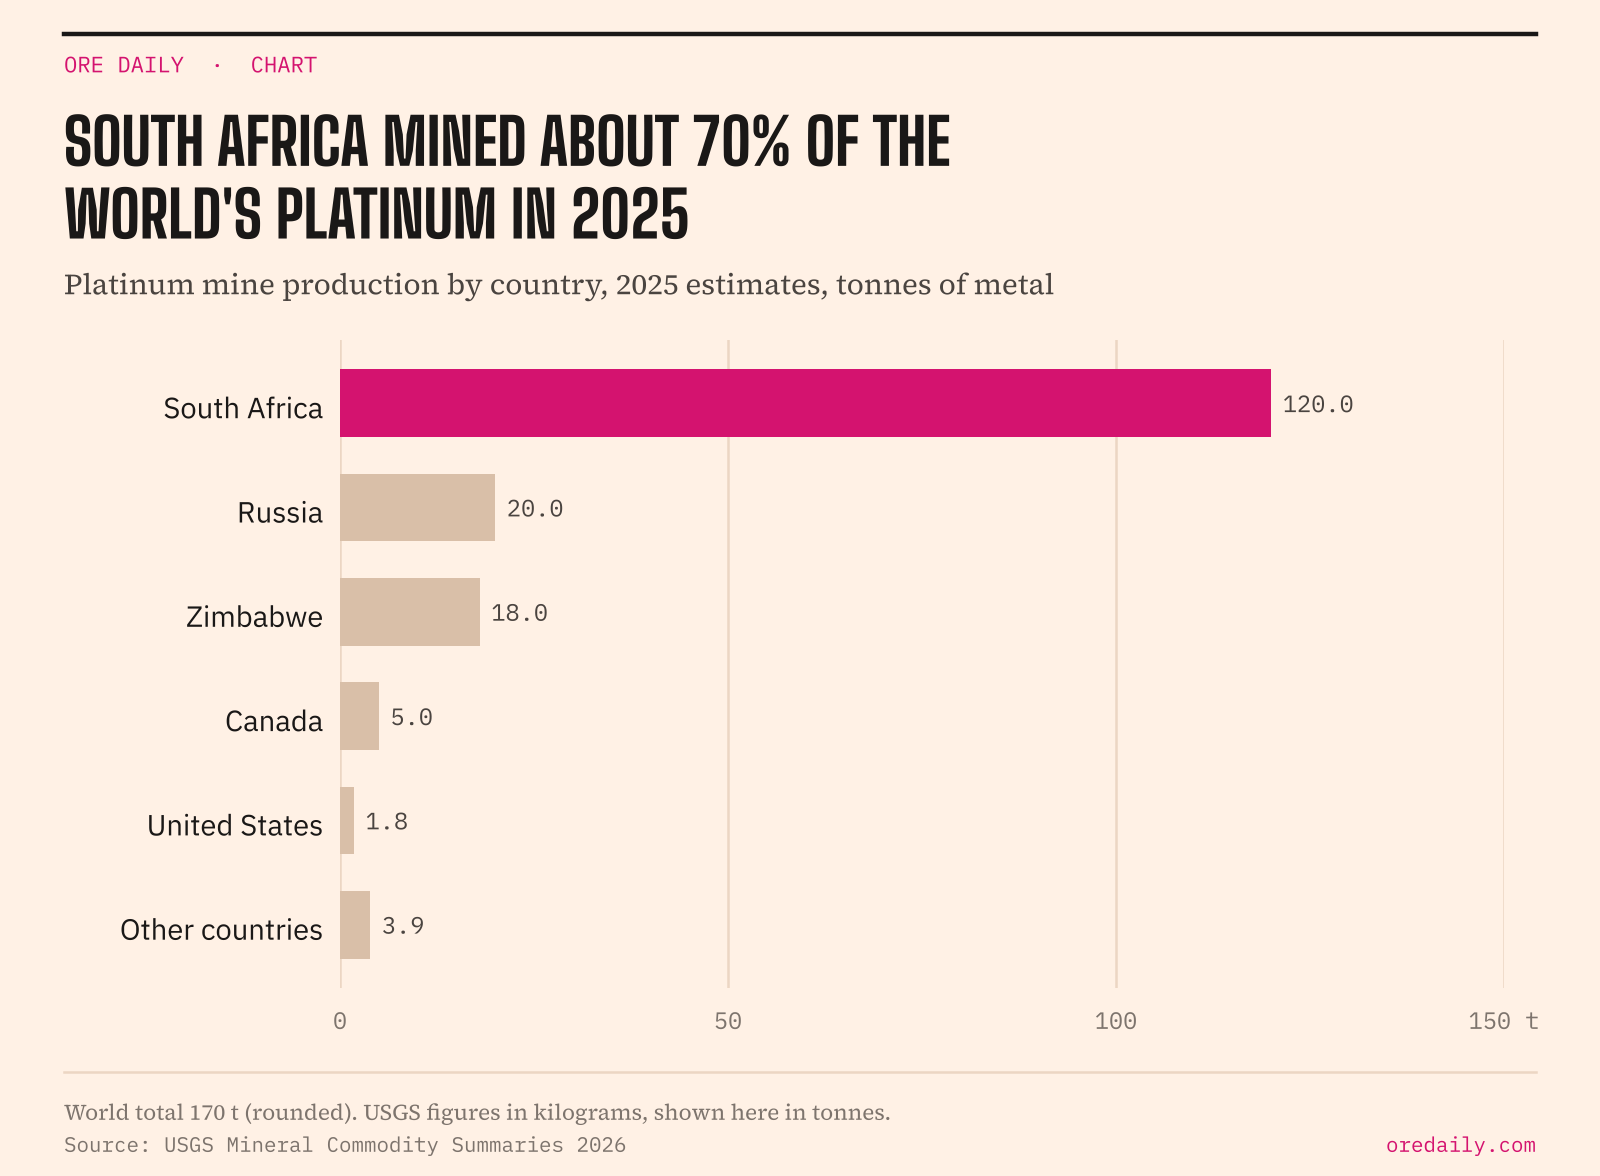
Valterra Platinum Q3: refined PGMs 576,900oz (−41%)
Maintenance and stock counts were shifted into the quarter; own-mine output −5% after safety stoppages; sales −27%. FY guide held at 3.0–3.4Moz, but unit costs are seen at the top of R19,000–20,000/oz on fuel and explosives costs. South Africa/PGMs.
Companies & deals10
Newmont–Barrick Nevada JV amended
Adds Barrick's Fourmile and Newmont's Fiberline and Mike to NGM; Newmont pays Barrick $1.95bn in Q4. Also: Cadia Q3 61koz (34koz in Q2) after the April seismic event; Tanami Expansion 2 slips to end-H1 2027; Q3 buybacks $1,779M. Nevada/gold.
Imperial Metals cuts Mount Polley 2026 guide
Now 16–18M lb Cu and 30,500–33,700oz Au after Phase 5 ore delays; consolidated guide held. BC.
Trafigura takes ~8.1% of Atico Mining
16.15M shares plus a US$16.4M convertible; ~19.9% partially diluted. Another trader buying equity for copper concentrate.
Hercules Metals C$30.0M bought deal
34.5M shares at C$0.87 (Canaccord, BMO) for the Hercules copper project, Idaho.
Denison takes 31% of Foremost's GR and Blackwing uranium properties
C$650,000 plus 1,031,191 warrants; Denison funds 80% of spending. Athabasca.
African Critical Elements completes Lepidico Canada purchase (80% of Karibib lithium, Namibia)
The 2020 DFS envisaged 4,900tpa LiOH; the first step is a local lepidolite concentrate plant under Namibia's raw-ore export ban. No timeline.
TSMC asks suppliers to test rare-earth-free motors (Reuters, 3 sources)
For factory automation equipment, as a hedge against Chinese magnet controls; early stage, and TSMC declined to comment. A sign of demand-side substitution from a major user ahead of Nov 10.
SQM restructures as "SQM Group"
Groups SQM, Novandino Litio (the Codelco JV) and SQM Litio Internacional.
Codelco tenders recovery of 1.5Mt of slag at the closed Ventanas smelter
Namib Minerals: non-binding US$30M Ecobank term sheet for Redwing gold, Zimbabwe
Markets5
Gold slides to lowest since Aug 4
Spot $4,060.37 (−1.9%) Oct 22 as oil and Fed-hike bets bite (CME FedWatch 86% for Dec); ~$4,023 in Asia Oct 23. Silver $55.72 (−3.9%), ~$54 Oct 23, the lowest since Nov 2025. Platinum $1,581.73 (−2.9%); palladium at a 16-month low. ASX gold index −5.56% Oct 23.
COMEX copper $6.4115/lb (−2.01%) Oct 22, low $6.35
Trading Economics links it to the tech/AI selloff and talk the US may drop the refined-copper tariff (unverified). China spot premiums are easing (North China average 260 yuan/t, SMM).
Other LME, Oct 22
Al $3,010 (−1%), Zn $3,670 (−2.2%), Ni $16,060 (−1%), Sn $50,330 (−1.7%).
Lithium carbonate 97,000 yuan/t (−2,350), −27% m/m
UpdateIndonesian nickel cuts
SMM now sizes the rumoured cuts at MHP 50%, matte 50% and NPI 20% (>20kt Ni/month from NPI), starting in November. Still no producer confirmation. MHP cash cost is ~$14,200–14,500/t vs spot below $13,000.
Drill hits10
Minaurum Silver: new blind Africa vein at Alamos (drill)
AL26-268 cut 2.05m @ 669 g/t AgEq (270 g/t Ag, 0.87 g/t Au), true width 1.75m; vein hit in 3 holes so far, none of it outcropping. Narrow; AgEq includes Au, Cu, Pb, Zn. Sonora, Mexico/silver.
Walker River / Nevada Canyon: thick gold at Lapon Canyon (drill)
LC-26-179 48.77m @ 2.02 g/t Au incl. 7.62m @ 6.61 g/t; LC-26-175 47.25m @ 2.07 g/t incl. 30.48m @ 3.07 g/t. Each ~98 g·m. True width not established. Nevada/gold.
Viridian Metals: 1.5km step-out hits at Kraken Main (drill)
VKS26-062 40.8m @ 0.63% CuEq (0.23% Cu, 0.20% Ni, 0.03% Co) incl. 15.7m @ 1.09% CuEq. Downhole lengths; CuEq. Labrador/Cu-Ni-Co.
IDEX Metals: first porphyry Cu-Mo hit at Solstice (drill, visual only)
KSMT26016 cut stockwork from ~300m to the end of the hole at 705.6m; the company calls it the first hole on the property to hit Cu-Mo inside a porphyry intrusion. Assays pending. Freeze, Idaho/Cu-Mo.
Alpha Exploration: new Obok prospect (drill)
ABD029 31.00m @ 1.12 g/t Au incl. 12.00m @ 2.09 g/t, at 60–85m vertical; ABD031 19.00m @ 3.18 g/t. True width ~70–90%. Aburna, Eritrea/gold.
Centaurus: two ~5km copper-in-soil corridors at Boi Novo/Rio Novo (surface)
Up to 3,500ppm and 2,000ppm Cu, coincident with FLEM conductors; Juruá rock chips up to 45 g/t Au (selective). No drilling yet. Carajás, Brazil/Cu-Au.
Ashley Gold: new Tic Tak copper zone (surface grab)
Grabs up to 3.43% Cu (selective); suspected visible gold in 4 of 10 holes, unconfirmed. Tak, next to Goliath, Ontario.
Decade Resources: bonanza boulders at Nobody Knows (surface, float)
Up to 79.12 g/t Au and 927 g/t Ag; 15 of 21 samples >10 g/t. A 165m soil anomaly plus VLF conductor outlines the source target. Selective; source not found. BC.
Canagold: Au-Sb at New Polaris (drill)
NP26-08 69.8 g/t Au over 2.6m within 4.64m @ 52.8 g/t Au and 0.83% Sb, from 503m; the company says most high grades sit outside the current resource. True width undetermined. BC/gold-antimony.
Adyton: copper strengthening at depth at Kabang (drill)
FDD033 109m @ 0.25 g/t Au, 0.18% Cu from 293m, incl. 20m @ 0.42% Cu; corridor now 2.2km. Apparent widths. Feni, PNG.
From X & analysts7
Saxo / Ole Hansen — copper selloff is "a deflation of previously elevated expectations,"
not a fundamental drop in demand: COMEX down 2.4% and below support near $6.50/lb on refined-copper tariff doubts and AI/data-centre capex worries, while electrification, grid spending and constrained mine supply still underpin it. On gold, stuck below $4,100 for the third time this month, managed money has cut net longs by 4Moz since Aug 25 while bullion ETF holdings rose 2.3Moz: "Speculative selling continues to more than offset strategic demand." Oct 22.
Marex / Alastair Munro: COMEX front-month now at a discount to LME,
which is pulling metal into LME sheds and explains the stock build. Reuters, Oct 22.
ANZ / Soni Kumari: "Gold prices can fall further"
as oil-driven inflation and hike bets dominate. Reuters, Oct 22.
Macquarie / Alice Fox: copper "way above where it ought to be given global stocks"
(LME Week remarks, cited in the ICA Australia brief of Oct 22; the brief expects $14,200–14,900 into November).
SP Angel: Indonesian HPAL MHP capacity to exceed 900kt contained Ni by end-2027,
with ore demand ~320Mt/yr against a 290Mt 2026 quota. This frames why the cut talk is happening. Oct 22.
@robert_ivanhoe (Friedland, Ivanhoe) — India as the overlooked copper demand driver
Cites a Government of India vision document: demand of 4–5Mtpa within 10 years, 9–10Mtpa after 20; <30kt primary output last year; "ONE new Kamoa-Kakula EVERY YEAR". The vision-document figures are not independently verified.
@robert_ivanhoe — claims China cathode premium hit a record $158/t on Oct 22
Unverified: the latest confirmed Yangshan print was $135 (Oct 9, a "four-year high"), and SMM shows domestic premiums easing this week.
Coming up, next 7 days7
Fri Oct 23 10:40 AM ET
Joly announces Strategic Response Fund money for Rio Tinto Alcan/Alouette (La Baie, QC).
Sat Oct 24
HVC strike deadline; China Northern Rare Earth Q3 (9M profit preview RMB3.62–3.68bn).
Sun Oct 25
Brazil runoff.
Tue Oct 27
Freeport Q3; IMARC Sydney opens.
Wed Oct 28
Agnico, Kinross, First Quantum Q3; Brazil PlanGeo consultation closes.
Thu Oct 29
Teck, Glencore, Vale, Lynas, Implats AGM; EIB-Canada Montreal Oct 29–30.
~Fri Oct 30
WGC Q3 Gold Demand Trends; Chile INE September output.