Top 5
1Highland Valley Copper strike notice
USW Local 7619 (about 1,200 workers) served 72-hour notice. A strike could start at 8 AM PT Sat Oct 24. HVC is Canada's biggest copper mine (2026 guide 115–135kt) and is mid-Anglo-Teck merger.
2Rio settles with CMRG; Fortescue left exposed
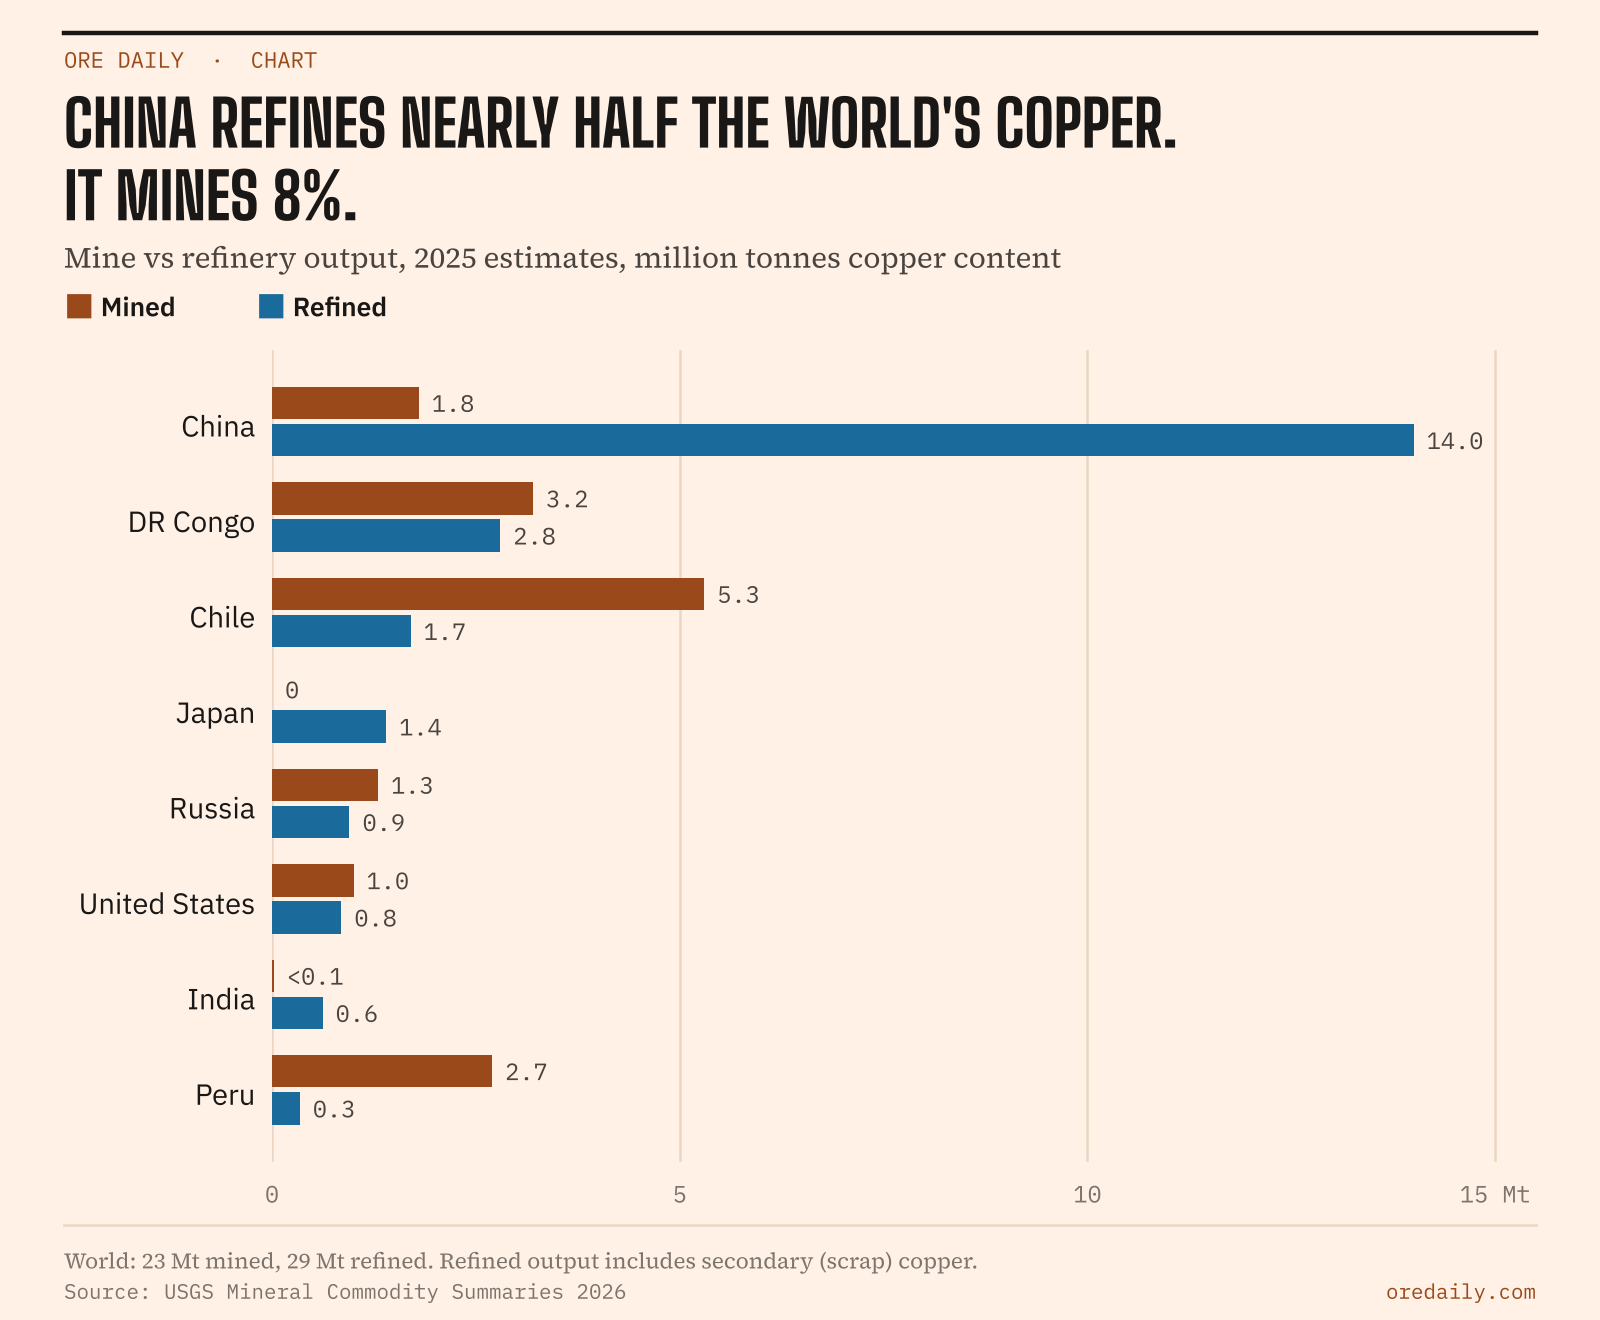
Sources say CMRG told mills on Oct 21 that it has a new Rio supply deal. Fortescue says operations "may be affected" if its own talks aren't done by year-end. China's state-buyer leverage is now visible in miners' results.
3UpdateCodelco overstated output — Chamber commission report approved 11-0
It blames the executives who "signed and authorized" the figures, not workers. Under-reported in English.
4Canada–Ontario tariff plan includes up to C$1bn federal for Ring of Fire roads, matching Ontario's C$1bn
It comes with joint permitting and a First Nations working group. Neskantaga and Attawapiskat say they will block construction.
5Lithium carbonate falls below 100,000 yuan
SMM spot is 99,350 yuan/t. GFEX most-traded contract is 94,180 (−5% w/w) as spodumene arrivals outrun demand. This erodes the 2026 recovery narrative.
Government & regulatory12
Canada–Ontario "C$8.7bn" action plan (Oct 21)
- Steel fund: C$3.55bn federal + C$1.67bn Ontario.
- Autos: up to C$1.5bn federal + up to C$1bn Ontario.
- Ring of Fire roads: up to C$1bn federal over 3 years.
- Priority projects can draw on the Critical Minerals Accelerator and the First and Last Mile Fund.
- The components add to C$9.72bn (C$8.72bn if road money is counted once). The PMO doesn't reconcile the total, and Bloomberg says some money was previously earmarked. Canada/Ontario; nickel, chromite, copper.
UpdateCodelco double-counting
The Chamber investigative commission (CEI) approved its report 11-0 on Oct 21.
- It calls the overstatement a "hecho de la mayor gravedad" and says planning began in June 2025. It concerns a correction of nearly 27,000t of 2025 copper.
- Recommendations: executive liability running for a year after leaving the board, and clarity on Cochilco's dual role.
- Separately, the Contraloría will deliver its 2025 output audit within about 2 months (Reuters). Chile; copper.
Chile: five more lithium tenders in 2027
Mining minister Mas said five private projects await approval (hoped for early 2027), with tenders for five more to follow. The target is to lift output from about 300kt/yr to 700kt in 5–10 years. Chile; lithium.
Brazil STF suspends Belo Sun Volta Grande licence
Justice Fachin froze the installation licence for the US$300M project (~3.8Moz reserves) until TRF-1 approves the Belo Sun–Funai settlement. He cited Indigenous impacts and cumulative pressure from Belo Monte. Pará; gold.
Malaysia approves first raw rare-earth export since the 2024 moratorium
One R&D/processing application was approved under the new October guidelines. Applicant, volume and destination were not disclosed. Malaysia; REE.
Sweden FDI screening kills Bacchus–Beowulf deal
The Inspectorate of Strategic Products discontinued its review without a binding agreement. Bacchus withdrew, and Beowulf (Kallak) sees "no prospect" of the investment; it is talking to Alumni Capital, and shares have been suspended since Oct 12. Under-reported. Sweden; iron ore/graphite.
China: no rare-earth signal yet before the Nov 10 expiry
Oct 22 SCIO 15th FYP briefing (Vice Commerce Minister Jiang Chenghua) mentioned only "improving export control" mechanisms. No MOFCOM text has formally moved the suspension of Nos 61/62 to Jan 10. China; REE.
Indonesia: Bahlil plan to "control production capacity" of nickel smelters
No rule or timeline yet. Analysts flag losses for standalone RKEF smelters (Bloomberg Technoz, Bahasa). Indonesia; nickel.
South Africa MTBPS: mining-led tax windfall
Provisional corporate tax is up over 17% in H1 2026/27, with mining the biggest contributor; June collections were R10.9bn higher y/y. Treasury calls it price-driven and short-term. The MRD Amendment Bill is still in drafting; the cadastre is due Mar 2027. SA; PGMs, gold.
UpdatePeru Ley MAPE bill sent to Congress (Oct 20, missed)
It sets up a consolidation regime from Jan 1, 2027 and a new agency, Formape, as the Reinfo successor. Peru; gold/ASM.
UpdateGhana cabinet approves revised Minerals & Mining Policy and Act amendments (Oct 19, missed)
to give Ghanaians a larger stake. Ghana; gold, bauxite, lithium.
Philippines: Chamber of Mines and the nickel industry association (PNIA) flag DOE-DENR Joint Administrative Order 2026-01
They say its bidding/evaluation rules may conflict with law and force incumbents to surrender assets. Mainly coal, but they cite a chill on critical-minerals FDI. Single-sourced.
Production & trade data5
China Sept cobalt metal trade (SMM, Oct 22)
- Imports about 642t (−37% m/m, −25% y/y), of which Indonesia 402t. Jan–Sep imports 10,416t (+93%).
- Exports about 527t, of which US 212t (+63% m/m). Jan–Sep exports 3,990t (−70%).
- China; cobalt.
China Sept tungsten trade
Concentrate imports 3,663t (+73% y/y); Jan–Sep concentrate+intermediate imports 29,614.6t (+87.7%). Raw/intermediate exports 1,058.3t (−12% y/y). WF6 exports 100.7t (+276% y/y). Published just before the window.
China Sept lithium (missed Oct 20)
Hydroxide exports 10,007.2t (+109% m/m) against imports 7,406.8t, so China flipped to net exports; Korea took 6,434.6t. Spodumene imports 970,100t (~81,300t LCE), with Zimbabwe 136,500t (+83%).
China yttrium oxide exports to Japan: 18t Jan–Sep (−98% vs 888t); 4t in Sept
Dy/Tb to Japan "negligible". This is likely the source of the X claim of "Dy −98%", which is unverified.
China Sept aluminium extrusion exports hit a record 92,700t (+26.5% y/y)
Companies & deals12
Teck HVC strike notice (detail)
Of 944 members who voted, all backed a strike, the local's strongest vote on record. The contract expired Sept 30. Teck tabled a revised money offer Oct 20; the union cites concessions on staffing, wages and pensions. Teck has contingency plans. BC; copper.
Fortescue Q1 FY27
- Shipments 46.8Mt (−6% y/y); sales 42.9Mt vs 47.5Mt consensus.
- C1 US$21.98/wmt (vs 18.17); realised US$79.79/dmt.
- FY27 guide of 197–207Mt held but "subject to" the CMRG outcome. CEO Otranto said about another 5Mt could go unsold and no West Pilbara Fines were sold.
- Shares hit their lowest since June 2025. Australia; iron ore.
Rio–CMRG iron ore deal
Volume and price were not disclosed. Reports differ on the term: "annual" per Mining.com sources, Nov 2026–May 2028 per Bloomberg via SP Angel. Single-sourced on terms.
BHP AGM
CEO Brandon Craig said plans support about 3–4%/yr group growth to 2035, with copper about 5%/yr. Copper is now more than half of earnings. Jansen first production is mid-2027, with opex about $120/t. Shareholders pressed on the $2.3bn Jansen Stage 2 write-down.
First Quantum: Kansanshi S3 tracking about 27Mt throughput in 2026 vs 25Mt design
2026 guide 175–205kt Cu, rising to 230–260kt by 2028. Zambia; copper.
IAMGOLD Côté to land at the low end of guidance
Q3 92.0koz (100%). 2026 attributable now expected at the low end of 270–310koz. Recovery was 90% because a Vertimill was down; a third Vertimill comes in early 2027. The mine tour is today. Ontario; gold.
UpdateNorthern Star new CEO Vadnagra flags possible asset sales
He is reviewing every asset and declined to comment on the Gold Fields bid. Barrenjoey names Jundee, Thunderbox and Carosue Dam as candidates.
Vault Minerals Sept qtr
- 76,849oz at AISC A$3,529/oz, above its FY guide of A$3,150–3,350.
- Paid a A$50.7M break fee on a terminated merger.
- Cash/bullion A$886.7M.
- Genesis merger on track for late Nov.
- Secondary source.
Nickel Industries Sept qtr
Record Hengjaya ore sales of 4.49Mwmt (+56% q/q). Adj. EBITDA US$125.9M. First MHP/cathode at ENC HPAL. Secondary source.
CME readies cash-settled tungsten futures
on Fastmarkets APT Rotterdam/Baltimore, targeting Q1 2027. CME metals volumes are up 41% y/y.
Glencore secures land access for Coroccohuayco (Oct 19, missed)
148ktpa Cu, first production targeted H2 2029. Peru.
European Lithium holders approve the Critical Metals Corp schemes (99.96%)
Austria/Australia; lithium.
Markets5
Copper
LME 3M closed Oct 21 at $14,370.5 (−0.59%, long liquidation). In Asia on Oct 22 it touched $14,260 on the AI-stock selloff, US tariff doubts and stalled Iran talks; the HVC strike risk partly offsets.
Gold
$4,084 (Kitco, −1.35%); the Asian low was $4,066. Brent above $111 after attacks in Saudi Arabia raises hike risk before the FOMC. Silver $55.74 (−3.65%).
Iron ore
SGX $89.8 (from $91.4), the lowest in almost two years; DCE 669 yuan (−1.83%).
Nickel
Up 3.7% Oct 21 to $16,095 (SP Angel) on unconfirmed talk of Chinese-led Indonesian cuts: about 50% of MHP/matte and 20% of NPI from November. Spot MHP is below $13,000/t Ni.
Lithium carbonate
99,350 yuan spot / 94,180 GFEX (see Top 5); spodumene $1,485 (SP Angel). Tin $50,325 (−1.7%). Cobalt flat.
Drill hits9
AbraSilver — Diablillos/Oculto East, Salta, Argentina (Au-Ag; drill)
DDH-26-061: 228m @ 1.79 g/t Au from 101m, including 11m @ 15.97 g/t. All oxide, outside the resource, about 50m below the pit design. Best gold intercept to date. True width unknown.
Austral Resources — Cameron River, Qld (Cu-Au; first-pass RC)
26WHRC004 (Waterhole): 15m @ 4.59% Cu, 1.16 g/t Au from 40m. Most of the six prospects were drilled for the first time in modern work. Downhole widths; geometry unconstrained.
Nine Mile Metals — Wedge VMS, Bathurst Camp, NB (Cu-Zn-Pb-Ag; drill step-out)
WD-26-18: 11.65m @ 7.13% CuEq of massive sulphide, including 4.80m @ 10.46%. The company says these are true widths; CuEq assumes 95% recovery.
Brightstar — Two Mile Hill, Sandstone, WA (Au; deep drill)
TMHDD26003: 305m @ 1.33 g/t from 584m, well below the 1.45Moz resource. The host tonalite is over 400m wide and still open. Downhole lengths; 0.25 g/t cut-off.
Gold Strike — Florin, Yukon (Au; drill, first hole of 11)
26F-01: 400m @ 0.53 g/t from 15m, including 50m @ 1.07 g/t. This is a bulk, low-grade, 2.5Moz inferred deposit. True width unknown.
Power Minerals — Morro do Ferro, Minas Gerais (REE; drill)
MFSR-054: 88m @ 6.33% TREO from surface, plus 2m @ 6.88% at 240m (the deepest high grade). Downhole widths; the summary has an internal inconsistency, so verify against the ASX filing.
Outcrop Silver — Santa Ana, Tolima, Colombia (Ag; drill, new vein)
The new parallel Cascada vein (DH687) ran 1,084 g/t AgEq over 1.37m (0.74m ETW). Alaska now reads as the northern extension, giving about 3km of strike. Widths are narrow.
Resource Minerals Intl — Wadi Salamah, Saudi Arabia (Au-Ag; surface rock chips)
Up to 7.93 g/t Au, 64.2 g/t Ag; 13 samples at or above 1 g/t over 1.4km of veins. There is also a 1.8×1.2km Bi-Mo soil anomaly. Selective chips; first RC drilling this quarter.
Endurance Gold — Reliance, BC (Au-Sb; drill step-outs)
DDH26-140: 5.2m @ 5.89 g/t Au, 0.19% Sb. 5 of 6 50m step-outs hit undefined footwall structures; about 80–100% true width.
Coming up, next 7 days6
Oct 22
Newmont Q3 after close (call 5:30 PM EDT); IAMGOLD Côté tour.
Oct 23
Zijin Q3 (briefing Oct 28); LME Week ends.
Oct 24, 8 AM PT
earliest HVC strike start. Oct 25: Brazil runoff.
Oct 27
Freeport Q3 call (10 AM EDT); IMARC Sydney Oct 27–29; FOMC Oct 27–28 (decision Oct 28).
Oct 28
Agnico, Kinross Q3; PlanGeo consultation closes. Oct 29: Teck Q3, Glencore Q3 production, Vale 3Q26, Lynas qtr, Implats AGM; EIB-Canada Montreal Oct 29–30.
Further out
Chile INE Sept mining ~Oct 30 (unconfirmed); China RE suspension expiry Nov 10; Indonesia RKAB window Nov 15.